CARI Captures Issue 765: Export arm of Indonesia’s sovereign wealth fund Danantara launches export monitoring platform


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


INDONESIA
Export arm of Indonesia’s sovereign wealth fund Danantara launches export monitoring platform
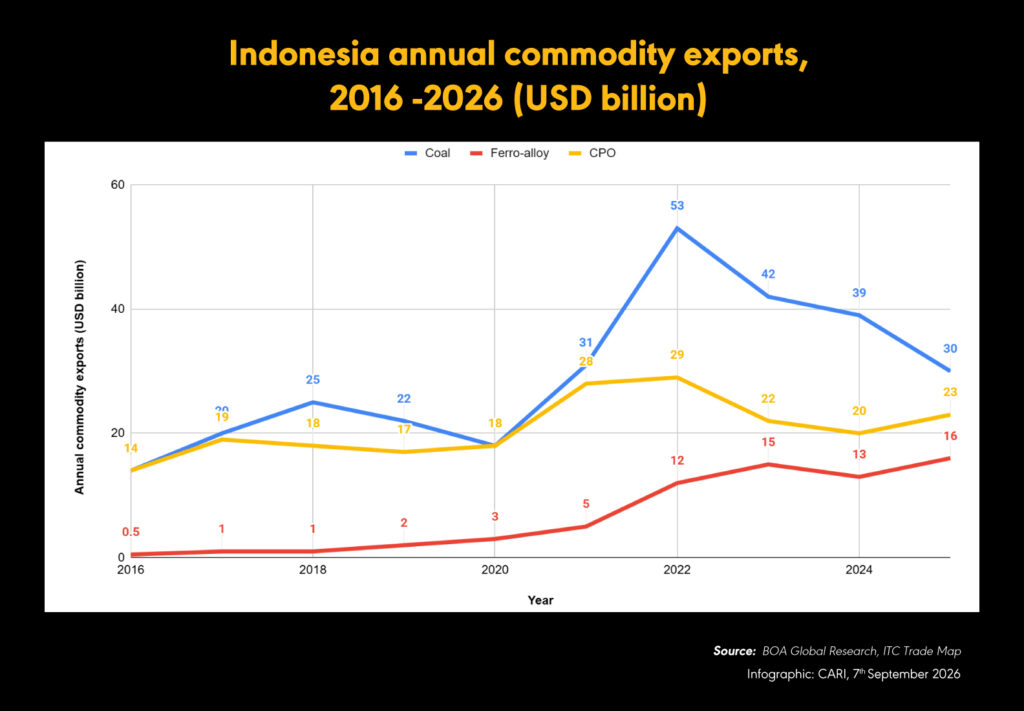
(31 August 2026) Danantara Sumberdaya Indonesia (DSI), the export arm of Indonesia’s sovereign wealth manager Danantara, is launching an export monitoring platform on 01 September covering coal, palm oil and ferro-alloys with combined annual trade flows exceeding USD 70 billion. The platform will verify export quantity, quality, classification, pricing, destinations, payment terms and repatriation of export proceeds, using integrated data from government agencies to identify potential under-invoicing and transfer pricing. DSI will act as an intermediary rather than the sole exporter, scaling back the government’s original proposal, with full implementation targeted by the end of 2026. Since beginning operations in June, DSI has monitored more than 6,500 export declarations covering about USD 14 billion in shipments. The framework could eventually expand to other commodities, although DSI said this would be gradual. Exporters and industry groups have sought greater clarity on reporting obligations, treatment of existing contracts, transition arrangements, pricing benchmarks and potential fees. Concerns are particularly significant for ferro-alloy producers because products such as ferro-nickel are traded through bilateral contracts with varying grades and specifications. President Prabowo Subianto’s plan to establish an Indonesian mineral and commodity exchange could eventually link DSI’s monitoring infrastructure to broader efforts to increase Indonesia’s influence over commodity pricing.

VIET NAM
Foreign franchises struggle to compete in Viet Nam’s beverage market
(01 September 2026) Viet Nam’s modern coffee and tea chain market reached an estimated USD 1.34 billion in 2025, with coffee chains growing 27% year-on-year to USD 725 million and tea chains rising 28% to USD 617 million, but foreign franchises continue to struggle to achieve large-scale expansion. Starbucks had 125 stores by end-2024 and surpassed 150 in January 2026, compared with 985 Highlands Coffee outlets by end-2025 and roughly 2,500 Milano Coffee locations. Chagee’s expansion was constrained after a March 2025 boycott over imagery containing China’s “nine-dash line” on its digital channels, while Café Amazon closed its remaining Vietnamese outlets in November 2025 after five years. Mixue has consolidated its Vietnamese store network following rapid franchising and intra-brand cannibalisation, while Gong Cha, KOI Thé, The Alley and Tiger Sugar remain at approximately 50 to 70 outlets each. Domestic operators increasingly compete across mass-market and premium segments, while Vietnamese consumers show willingness to pay premium prices for product quality, atmosphere and social experience rather than foreign brand origin alone. The article identifies market saturation, rapid local imitation, entrenched domestic supply chains and real-estate networks, and geopolitical reputational risks as major constraints on international expansion. It concludes that strong product-market fit alone is insufficient for foreign chains to achieve category-defining scale in Vietnam’s highly localised and competitive beverage market.

VIET NAM, THE PHILIPPINES
Viet Nam and the Philippines intensify engagement to address issues in bilateral rice trade
(30 August 2026) Viet Nam intensified engagement with Philippine authorities from 19-21 August to address issues in their bilateral rice trade, particularly the Philippines’ safeguard investigation into imported rice. A Vietnamese inter-sectoral delegation led by the Deputy Minister of Industry and Trade met the Philippines’ DTI, DFA, Tariff Commission and Department of Agriculture. Both sides agreed to continue implementing the existing MoU on rice trade cooperation, maintain information exchanges and minimise adverse effects on bilateral trade. Viet Nam proposed upgrading the MoU or establishing a more legally binding and stable framework for long-term rice cooperation, which the Philippine side agreed to study. The Tariff Commission said the safeguard investigation would be conducted fairly and transparently under WTO and ATIGA rules and requested continued Vietnamese participation in a public hearing scheduled for September 2026. Viet Nam urged the commission to consider Philippine import policies, including lower tariffs and SPS import clearances, and the role of imported rice in supply, price stability, and food security. The Philippine side reiterated that Viet Nam remains a stable major rice supplier despite efforts to diversify import sources. The Vietnam Food Association and Philippine Rice Industry Association also agreed to strengthen information sharing, business links and coordination on commercial difficulties.

THE PHILIPPINES
Philippine peso falls to record low against US dollar amidst pressure of high oil prices
(31 August 2026) The Philippine peso fell 37.7 centavos to a record closing low of 62.265 per US dollar on Friday, extending three straight weeks of losses for the peso and surpassing the previous record of 61.888 set the previous day. The peso has lost nearly 8% since the Iran war began on 28 February, with higher oil prices increasing pressure on the Philippines’ import-dependent economy and inflation outlook. The Bangko Sentral ng Pilipinas raised its benchmark interest rate by 25 basis points to 5%, bringing total tightening in the current anti-inflation campaign to 75 basis points, but the currency remained under pressure. The Philippines’ Governor described the increase as pre-emptive, while policymakers forecast average inflation of 6.1% in 2026 and 5.4% in 2027. Citi analysts said external pressures, including higher energy prices, a widening current-account deficit and weaker services balance, could persist, with infrastructure spending expected to keep imports elevated. A weaker peso may increase the local value of remittances and improve export competitiveness, but it will raise import costs and increase peso-denominated repayment costs for foreign-currency debt.

BRUNEI DARUSSALAM, MALAYSIA
Malaysia-Brunei Darussalam bilateral trade reaches MYR 5.86 billion in 2025
(01 September 2026) Brunei Darussalam was Malaysia’s sixth-largest ASEAN trading partner in 2025, with bilateral trade reaching MYR 5.86 billion, while trade totalled MYR .38 billion in January-June 2026. Malaysia’s High Commissioner to Brunei Darussalam highlighted a newly signed memorandum of understanding between the National Chamber of Commerce and Industry of Brunei Darussalam and the National Chamber of Commerce and Industry of Malaysia to strengthen business networks and commercial exchanges. He encouraged Malaysian businesses in Brunei Darussalam to use the platform to identify new opportunities and support bilateral economic growth. Prime Minister Anwar Ibrahim’s 22 August visit to Brunei Darussalam for the 27th Annual Leaders’ Consultation provided the highest-level bilateral platform for both countries to discuss mutual interests and future cooperation. During the visit, Sultan Hassanal Bolkiah conferred the Darjah Kerabat Laila Utama Yang Amat Dihormati (D.K.) on Anwar, which the high commissioner described as reflecting the strength of bilateral relations.

MALAYSIA
Bank Negara Malaysia keeps overnight policy rate at 2.75%, with eye on price stability and continued growth
(03 September 2026) Bank Negara Malaysia (BNM) kept the overnight policy rate (OPR) at 2.75% at its fifth of six scheduled reviews for 2026, in line with expectations from 20 of 22 economists polled by Bloomberg. BNM said the current policy stance remains consistent with continued price stability and sustainable economic growth. Malaysia’s economy expanded 6.0% year-on-year in the second quarter of 2026, accelerating from 5.4% in the first quarter, supported by resilient household spending and strong exports. BNM expects solid momentum to bring 2026 growth to around 5%, with sound fundamentals supporting resilient growth in 2027. The external sector is expected to benefit from improved global prospects, robust demand for electrical and electronics goods, continued strength in technology-related exports and sustained tourist spending. BNM noted that higher costs and strong economic growth are creating increasing inflation pressures. Consumer price increases have so far been contained by domestic policy measures, stable demand and limited spillover from external-sector strength into wages.

THAILAND
Fitch Ratings assessing whether to restore Thailand to stable rating
(03 September 2026) Fitch Ratings is assessing whether Thailand’s improving political and economic conditions justify restoring a stable outlook on its BBB+ sovereign rating, after lowering the outlook nearly a year ago. The senior director of Fitch said the balance of risks has improved, citing greater political stability and economic resilience. Prime Minister Anutin Charnvirakul’s government has consolidated power following February’s election, while periods of political stability have strengthened the credibility of medium-term fiscal plans and potential reforms. Gross general government debt has stabilised at about 60% of GDP, above the 57% median for BBB-rated sovereigns, after rising by about 25 percentage points since 2019. The government expects about USD 12 billion (MYR 48.54 billion) of emergency borrowing linked to the Middle East conflict to remain within its fiscal framework and keep debt below the 70% ceiling. Fitch is likely to raise its 1.8% 2026 growth forecast, supported by fiscal stimulus and stronger investment, while the Ministry of Finance has raised its forecast from 1.6% to 2.5%. Fitch is assessing whether improvements in growth, debt dynamics and the political environment can be sustained over the medium term. Infrastructure improvements and a stronger business climate could support higher growth, although the longer-term economic impact of increased data-centre investment remains uncertain. New revenue measures, including a delayed value-added tax increase, appear unlikely while the government continues to favour stimulus. Fitch’s previous review was published on 24 September 2025, and they did not indicate when the next assessment would take place.


RCEP Monitor


NEW ZEALAND
New Zealand Dollar falls 0.9% against US Dollar after central bank raises rates
(02 September 2026) The New Zealand dollar fell 0.9% against the US dollar to 0.5839, its lowest level since 13 August, after the Reserve Bank of New Zealand (RBNZ) raised its benchmark interest rate by 25 basis points to 2.75%. The increase was approved unanimously by all six Monetary Policy Committee members and marked the second consecutive rate hike, taking the policy rate to its highest level since August 2025. The RBNZ said inflation reached 4.1% in the second quarter, driven by higher fuel and energy prices linked to the Middle East conflict, which warranted further tightening by the RBNZ to return inflation to its 1%-3% target. The central bank expects inflation to return to 2% by late 2027 as the fuel-price shock fades. It also noted weak second-quarter economic growth and rising unemployment, indicating pressure on the labour market. The RBNZ’s governor said there is no predetermined path for monetary policy and that the timing of any further increase remains uncertain. The governor said the RBNZ may need more time to assess the policy stance and that the current rate is approaching neutral. Market pricing for another 25-basis-point increase at the October meeting fell below 50% following the decision. Investors are expected to reassess rate expectations using forthcoming inflation, unemployment and economic growth data.

JAPAN
Yen strengthens to one-month high amidst expectations of government intervention
(03 September 2026) The Japanese yen strengthened to a one-month high, with the dollar falling 1.0% to 157.14 yen after reaching 156.34 yen, amid speculation that Japanese authorities may have checked exchange rates as a precursor to intervention. Expectations have increased that the Bank of Japan (BOJ) could adopt a more hawkish stance at its policy meeting later this month. A board member of the BOJ said rate increases should be conducted in a “nimble and data-dependent” manner, indicating that tightening may not continue at the previous roughly six-month interval. Markets have largely priced in a 25-basis-point increase, while some investors are considering the possibility of a larger hike to support the yen. Higher Japanese rates could narrow the Japan-US interest-rate gap and reduce the attractiveness of yen-funded carry trades, potentially increasing demand for the currency as such positions are unwound. The MUFG said a hike would confirm a shift towards quarterly tightening, while further acceleration could occur before any unusually large increase. US Treasury Secretary Scott Bessent has also urged Japan to move away from reflationary policies, reinforcing expectations of faster BOJ tightening. Weaker US economic data and dovish comments from a Federal Reserve official have reduced expectations of an immediate US rate increase and added pressure on the dollar against the yen. Intervention concerns are heightened by the upcoming US Labor Day holiday, when thinner foreign-exchange trading could amplify the impact of any Japanese intervention.

SOUTH KOREA
South Korea’s consumer price index rises 3.1% year-on-year in August 2026
(02 September 2026) South Korea’s consumer price index (CPI) rose 3.1% year-on-year in August, accelerating from 2.8% in July but below economists’ 3.2% forecast. Public-service prices increased 6.5%, largely due to a 26.7% rise in mobile service fees following temporary discounts introduced a year earlier. Petroleum prices rose 14.2%, easing from 15.5% in July. The Finance Ministry said inflation would have been 2.5% excluding the one-off mobile fee effect, while nationwide fuel price caps reduced August inflation by 0.3 percentage points. Monthly CPI increased 0.2%, compared with a 0.2% decline in July and below the 0.3% forecast. Core CPI, excluding volatile food and energy prices, accelerated to 3.4% year-on-year from 2.6%, its fastest increase since May 2023. The ministry expects headline inflation to ease in September, although the Bank of Korea expects continued upward pressure on core goods prices. The data follows the Bank of Korea’s second consecutive interest-rate increase last week as inflation remained above target alongside financial-stability risks.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 764: ASEAN data centre investments to increase from USD 15.72 billion in 2025 to USD 35.08 billion in 2031


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN
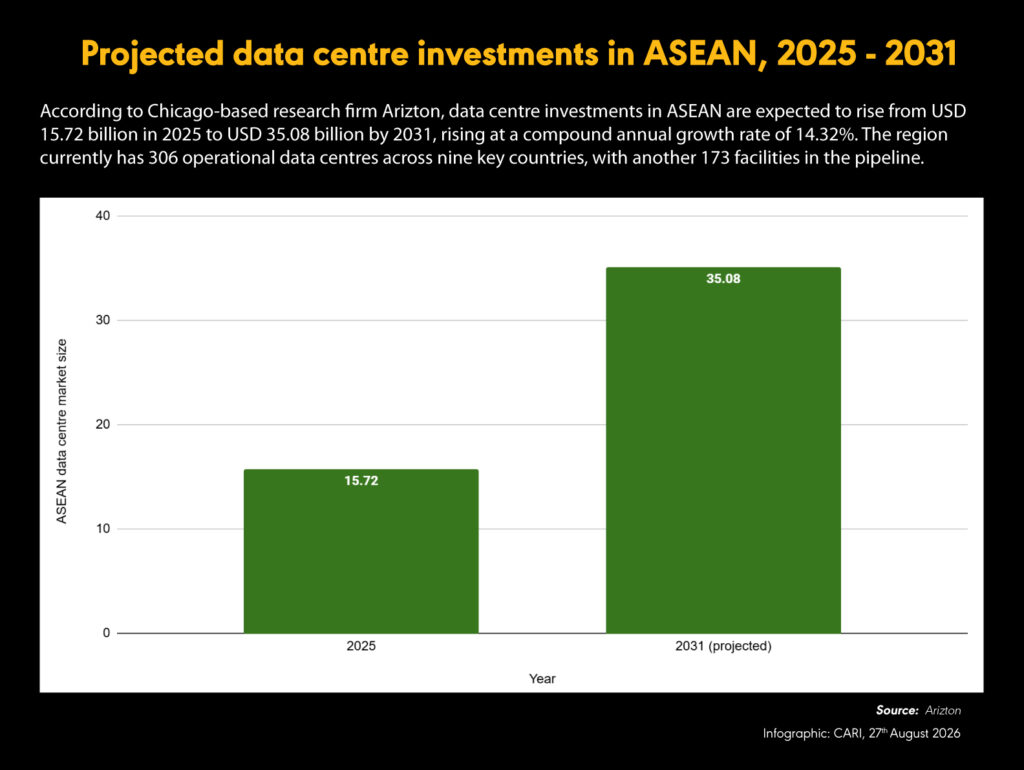
ASEAN data centre investments to increase from USD 15.72 billion in 2025 to USD 35.08 billion in 2031
(25 August 2026) According to Chicago-based research firm Arizton, Southeast Asia has 306 operational data centres and 173 in the pipeline, while regional data centre investment is forecast to increase from USD 15.72 billion in 2025 to USD 35.08 billion by 2031, a 14.32% CAGR. Arizton forecasts 1,435 MW of regional capacity and 5.83 million sq ft of white-floor space by 2031. Malaysia has the largest announced pipeline, exceeding 6 GW of IT load, including about 4.0 GW in Johor as of November 2025, of which 700 MW was under construction and 3.3 GW remained planned or announced. Malaysia’s market is forecast to reach USD 11.40 billion and 679 MW by 2031, supported by lower electricity and construction costs than Singapore and investment incentives. However, new data centre tariffs introduced in July 2025 could increase energy costs by 10–14%, with facilities above 100 MW facing an additional USD 15–20 million in annual costs. Singapore has 45 operational data centres and six upcoming facilities, with future development focused on efficiency and density; it also approved a 700 MW low-carbon data centre park on Jurong Island last October. Thailand is forecast to be the fastest-growing market, rising from USD 1.44 billion to USD 6.28 billion by 2031 at 27.78% CAGR, with a pipeline exceeding 2.87 GW and four projects approved for about 376 MW last November. Indonesia is forecast to grow from USD 2.82 billion to USD 6.09 billion by 2031 and has 88 operational and 25 upcoming facilities, with Batam attracting cloud and AI infrastructure investment including a planned 360 MW Firmus facility. Arizton expects regional AI computing requirements to increase nearly tenfold by 2030, driving capacity to almost triple, while submarine connectivity is also expanding across Singapore, Indonesia and Malaysia.

VIET NAM, AUSTRALIA
Viet Nam and Australia focusing on strengthening bilateral trade and investments
(26 August 2026) The Australia-Vietnam Policy Institute Forum in HCM City on 25 August focused on strengthening bilateral trade and investment to support Viet Nam’s rapid growth agenda. The Australian Consul-General said Viet Nam recorded 8% growth in 2025 and is shifting towards innovation-led growth, with Resolution 10 prioritising high-quality investment, skills development, technology transfer and national resilience. Australia aims to become a trusted long-term economic partner and identified the Australia-Vietnam Comprehensive Strategic Partnership and South-East Asia Economic Strategy to 2040 as key policy frameworks for deeper cooperation. The Permanent Vice Chairman of the HCM City People’s Committee, said leaders reaffirmed bilateral priorities in the economy, trade, investment, and science, technology and innovation during General Secretary To Lam’s 9–12 August visit to Australia. The Vice Chairman said the National Assembly’s passage of the Urban Development Law on 24 August provides a legal framework to mobilise domestic and international resources for urban and special economic zone development, potentially supporting greater Australian investment in HCM City.

VIET NAM, MYANMAR
Viet Nam and Myanmar agree to raise bilateral trade to USD 1 billion from USD 591 million in 2025
(27 August 2026) Viet Nam and Myanmar agreed to raise bilateral trade to USD 1 billion from USD 591 million in 2025, an increase of about 69%, during the Vietnamese Foreign Minister’s visit to Naypyidaw. Two-way trade reached USD 395 million in the first seven months of 2026, up 25% year on year, indicating a recovery from USD 591 million in 2025 and USD 873.9 million in 2018. The two countries had previously approached the USD 1 billion target, with trade reaching USD 952 million in 2019. Myanmar pledged favourable conditions for Vietnamese companies, particularly in telecommunications, education and training, agriculture and food processing. Vietnamese firms already operating in Myanmar include Mytel, BIDV and Hoang Anh Gia Lai. The two sides also agreed to simplify customs procedures and expand cooperation in telecommunications, agriculture and digital transformation. They will reconvene their Joint Committee on Bilateral Cooperation in 2027, the first such meeting since 2019. Myanmar President Min Aung Hlaing thanked Viet Nam for supporting Myanmar’s cooperation with ASEAN. The visit was Le Hoai Trung’s first bilateral visit to Myanmar since the 2021 military takeover.

MALAYSIA
Malaysia mulling regulations for e-commerce platforms, including registration requirements
(26 August 2026) Malaysia is considering immediate measures to regulate e-commerce platforms, including a registration requirement, following complaints from users and merchants. Malaysia’s Communications Minister said on 26 August that some platforms operating in Malaysia have not registered their companies locally, although he did not identify them. Prime Minister Anwar Ibrahim instructed the Finance and Communications Ministries to examine regulatory measures during a Cabinet meeting. Malaysia’s internet regulator has received 1,964 complaints about e-commerce platforms since January 2025, covering scams, electrical and electronic products, and halal certification issues. Fahmi said enforcement would begin immediately but did not provide details of the proposed measures. Popular platforms in Malaysia include Shopee, TikTok Shop and Lazada.

MALAYSIA
Business confidence for third quarter of 2026 improves to 5.9% from -1.8% in previous quarter
(27 August 2026) The Department of Statistics Malaysia (DOSM) reported that business confidence for 3Q2026 improved to 5.9%, from negative 1.8% in 2Q2026, with all major sectors recording stronger readings except for a slight easing in services. Industry posted the largest improvement, rising to 8.2% from negative 3.7%, while construction moved to 4.1% from negative 9.5% and wholesale and retail trade to 1.2% from negative 7.5%. Services remained positive at 5.2%, compared with 6.2% previously. The overall six-month outlook also strengthened, with the net balance increasing to 12.9% from 7.9%. Construction had the strongest six-month outlook at 23.3%, followed by industry at 14.3%, services at 13.1% and wholesale and retail trade at 5.3%. For 3Q2026 revenue, 31.9% of businesses expect an increase, 47.4% expect no change, and 20.7% anticipate a decline. Employment expectations remained broadly stable, with 78.3% of businesses expecting no change in workforce, while 13.9% plan to increase hiring and 7.8% expect reductions. At the state level, Terengganu recorded the highest confidence reading at 10.5%, followed by Kuala Lumpur at 9.5% and Negeri Sembilan at 9.4%. Melaka and Labuan were the only states with negative readings, at negative 3.9% and negative 5.4% respectively.

THAILAND
Bank of Thailand keeps policy rate unchanged at 1.00% on 26 August
(26 August 2026) The Bank of Thailand’s monetary policy committee unanimously kept its policy rate at 1.00% on Wednesday, marking the third consecutive meeting without a change. The decision reflects subdued domestic demand, high household debt and weak, below-potential growth, which give policymakers scope to prioritise economic recovery despite higher energy costs linked to the Middle East conflict. The BOT said exports and investment have benefited from the technology and artificial-intelligence cycle, but these gains rely heavily on imported inputs and have limited spillovers to the wider economy. The central bank forecasts GDP growth of 2.3% in 2026 and 1.8% in 2027. It now expects headline inflation to be lower than previously assessed because of fluctuations in global energy prices, compared with earlier forecasts of 2.8% in 2026 and 1.4% in 2027. The BOT will monitor the Middle East conflict, the extent to which businesses pass higher costs to consumers and medium-term inflation expectations. The committee said the current 1.00% rate remains appropriate to support economic recovery. Capital Economics expects rates to remain unchanged for the rest of 2026, with easing potentially resuming in 2027 if inflation declines as forecast.

THE PHILIPPINES
Companies adjusting as inflation and weak growth pressures consumer spending
(26 August 2026) Philippine companies are adjusting pricing, product inputs, expansion and promotions as inflation, a weak peso and subdued growth pressure consumer spending. Shakey’s Pizza Asia Ventures reported a one-third decline in first-half profit and is slowing expansion, becoming more selective on investment and restructuring its Peri-Peri chicken chain. Jollibee Foods cut its same-store sales, profit-growth and outlet-opening forecasts despite improved customer visits in April–June, while retaining lower-priced Mix & Match meals and implementing a PHP 2.8 billion-peso cost-containment programme. Monde Nissin is switching to lower-cost ingredients and staggering 1–5% price increases by product. Century Pacific Food raised prices 4–5% after holding them unchanged for two years and plans smaller increases in the third quarter. San Miguel Food and Beverage is controlling costs, expanding capacity where demand is stronger, and maintaining lower-priced food lines. PLDT’s Smart Communications increased selected prepaid packages to PHP 109 from PHP 99 while adding data and benefits, while PLDT Home introduced additional lower-cost broadband speed options. Globe Telecom is using free service periods, speed upgrades, and targeted discounts, including 30 days free, triple speeds and PHP 100 discounts for selected customers. Philippine Seven expects to benefit from consumers shifting towards cheaper products and nearer stores, and is expanding provincial branches while increasing its focus on ready-to-eat food and proprietary drinks.


RCEP Monitor


AUSTRALIA
Household spending rises 1.1% month-on-month in July 2026
(27 August 2026) Australian household spending rose 1.1% month on month in July, almost four times the 0.3% economist forecast, according to Australian Bureau of Statistics data. Spending was 7% higher than a year earlier, compared with an expected 5.7% increase. The figures indicate continued consumer demand despite the Reserve Bank of Australia’s three interest-rate increases at the start of 2026. The RBA has since held its policy rate at 4.35% at its past two meetings while seeking to reduce inflationary pressure. The stronger spending data, following a higher-than-expected inflation reading on Wednesday, has increased expectations that the RBA could raise rates again as early as September. Oxford Economics Australia said continued household spending strength would concern the RBA, although falling house prices and the prospect of further rate rises could weaken demand. July unemployment also increased, suggesting some easing in labour-market conditions. Markets and economists will assess next week’s second-quarter GDP data and subsequent labour-market figures for further indications of the RBA’s policy direction.

JAPAN
Authorities mulling using tax incentives to encourage retail purchases of government bonds
(27 August 2026) Japan is considering tax incentives to increase individual purchases of government bonds, potentially shifting household wealth from bank deposits into sovereign debt. Proposals include inheritance-tax breaks for Japanese government bond holdings and a Democratic Party for the People (DPP) bill to allow government bonds in NISA tax-free investment accounts. As of March, households held about JPY 20 trillion (USD 125 billion) in government bonds against JPY 1 quadrillion in bank savings, according to Bank of Japan data. The five-year bonds due for issuance in September will carry a 2.06% coupon, compared with about 1% on five-year fixed deposits at major banks. Retail government bond sales reached about JPY 4 trillion between April and August, up 66% year on year. Japan’s Finance Minister said making government bonds more attractive to retail investors was necessary for stable issuance and redemption as the BOJ reduces its bond purchases. Mizuho Securities estimated that inheritance-tax incentives could trigger reallocations of tens of trillions of yen or more than JPY 100 trillion, particularly among wealthy households. He noted that shifting bank savings into government bonds could reduce commercial banks’ capacity to buy government debt, limiting any net increase in overall demand. The NLI Research Institute also noted that NISA is intended primarily to redirect savings towards equities and provide companies with growth capital, rather than support government financing. Daiwa Institute of Research warned that large tax incentives would create a fiscal cost.

SOUTH KOREA
Bank of Korea raises benchmark interest rate by 0.25 percentage points to 3% on 27 August
(27 August 2026) The Bank of Korea raised its benchmark rate by 0.25 percentage points to 3% on 27 August, with six of seven Monetary Policy Committee members supporting the increase. The move followed a similar 0.25-point increase in July and ended a period in which rates had remained at 2.5% since May 2025. The BoK raised its core inflation forecasts to 2.5% for both 2026 and 2027, from 2.4% and 2.3% respectively. It also upgraded GDP growth forecasts to 3.3% for 2026 and 2.9% for 2027, from 2.6% and 2.1%, driven by strong semiconductor exports and investment and a gradual consumption recovery. The central bank warned that stronger household incomes could increase demand-side inflation and highlighted rising metropolitan housing prices and household debt as risks. The BOK’s Governor said the latest increase was intended to address inflation before stronger measures became necessary. The BoK’s new dot plot indicated a slower pace of further tightening, with 10 of 21 projections pointing to a 3.25% rate in six months, six to 3.5% and five to 3%. The won strengthened to KRW 1,379 per US dollar following the decision, while the Kospi rose 1.58%. Meanwhile, the government expects 2027 national tax revenue to exceed KRW 500 trillion (USD 362 billion), up from a previous KRW 412 trillion forecast, supporting plans for a Future Response Fund targeting AI and other strategic industries.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 763: Viet Nam surpasses Thailand to become ASEAN’s second-largest aviation market in August 2026


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN
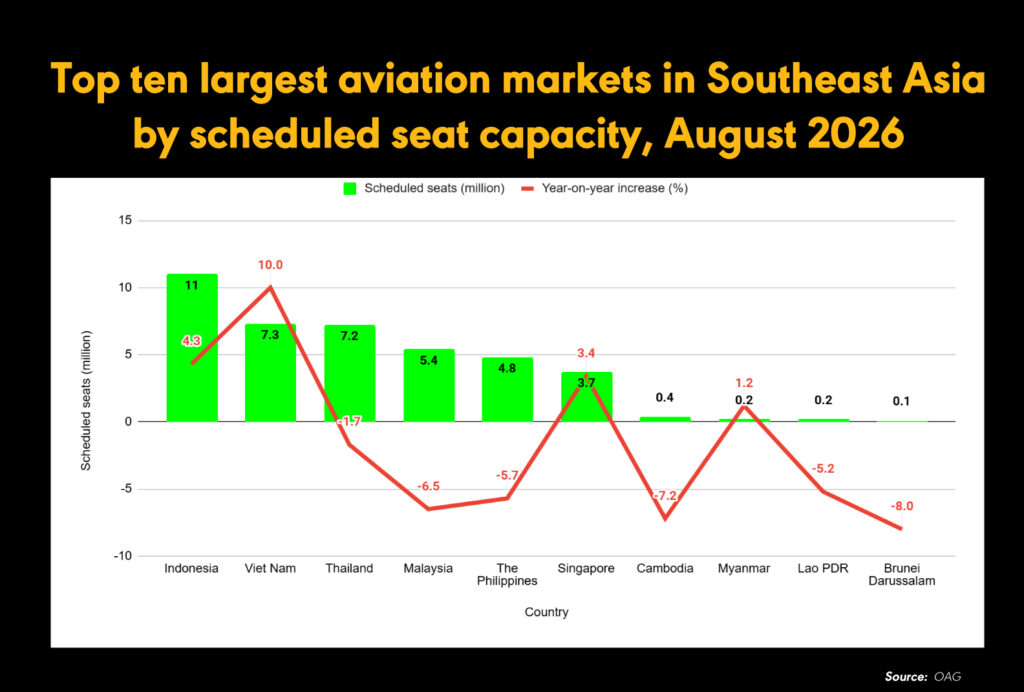
Viet Nam surpasses Thailand to become ASEAN’s second-largest aviation market in August 2026
(16 August 2026) Viet Nam became Southeast Asia’s second-largest aviation market for the second consecutive month, with 7.3 million scheduled seats in August, surpassing Thailand’s 7.2 million, according to British aviation analytics firm OAG. Indonesia remained the largest market with around 11 million seats, up 4.3% year-on-year. Southeast Asia’s total airline capacity reached around 51 million seats, an annual increase of 0.8%. Malaysia ranked fourth with 5.4 million seats, followed by the Philippines with 4.8 million. Indonesia also remained the region’s largest domestic market, with 8.8 million seats, up 5.4% year-on-year. Viet Nam recorded the fastest capacity growth among the five largest markets at 10%, while Thailand, Malaysia and the Philippines declined 1.7%, 6.5% and 5.7%, respectively. Lion Air was scheduled to provide around 2.33 million seats, ranking third in Southeast Asia behind Vietnam Airlines and AirAsia, although its capacity fell 11.1% year-on-year. Batik Air was among the airlines supporting growth in the region’s full-service segment. International capacity from Southeast Asia to Europe and North America increased 10.8% and 9%, respectively, while capacity to the Middle East declined 4.6%.

MYANMAR
Myanmar President Min Aung Hlaing departs for Russia on 17 August for first official visit
(17 August 2026) Myanmar President Min Aung Hlaing departed for Russia on 17 August for his first official visit since assuming the presidency in April. The visit includes a Myanmar-Russia business forum attended by the chief minister of Tanintharyi region and the head of Myanmar’s aerospace agency. Russia is seeking to expand energy investments in Myanmar following a 2025 agreement to build a small-scale nuclear power plant and a February 2025 memorandum on investment cooperation for the Dawei Special Economic Zone covering a port and oil refinery. The visit marks Min Aung Hlaing’s fifth foreign trip as president, following visits to India, China, Lao PDR and Thailand. Defence cooperation has continued to deepen, with Russia providing military training, university scholarships and arms supplies, while earlier this year agreeing to help train Myanmar’s first cosmonaut.

THAILAND
Economy grows 1.9% year-on-year in April-June quarter, marking weakest growth in three quarters
(17 August 2026) Thailand’s economy grew 1.9% year-on-year in the April-June quarter, slowing from 2.8% in the previous quarter and marking its weakest growth in three quarters, according to the NESDC. Growth was supported by strong electronics exports linked to global demand for AI-related products and a government shopping subsidy, while higher energy prices and disruptions to travel weighed on activity. Private consumption growth slowed to 1.9% from 3.3%, while private investment accelerated to 13.4% from 10.1%. Government investment contracted 1.6% after expanding 9.4% in the first quarter. Foreign tourist arrivals totalled 18.4 million in January-July, down 3% year-on-year, with arrivals from the Middle East, Europe and nearby markets affected by flight cancellations. The NESDC raised its full-year growth forecast to 2.0%-2.5% from 1.5%-2.5%, but said uncertainty remained, particularly over the Middle East conflict and energy prices. Economists state that second-half growth will be difficult to predict. In comparison, second-quarter growth slowed in Indonesia to 5.29% from 5.61% and the Philippines to 2.3% from 2.8%, while Singapore grew 5.9%, Viet Nam 8.4% and Malaysia 6.0%.

MALAYSIA
Inflation eases to 1.8% year-on-year in July 2026 from 1.9% in June
(17 August 2026) Malaysia’s inflation eased to 1.8% year-on-year in July 2026 from 1.9% in June, with the Consumer Price Index rising to 137.1 points from 134.7 a year earlier, according to DOSM. Transport remained the main contributor, although its inflation rate slowed to 1.4% from 2.8%. Inflation also moderated in personal care, social protection and miscellaneous goods and services to 2.9%, restaurant and accommodation services to 2.0%, and insurance and financial services to 1.1%. In contrast, information and communication inflation rose to 3.4% from 2.4%, while food and beverages and housing, water, electricity, gas and other fuels increased to 1.8% from 1.4%. Of 573 items, 374 or 65.3% recorded price increases, with 367 registering increases of 10% or less, while 157 items declined and 42 were unchanged. Seven states recorded inflation above the national rate, led by Negeri Sembilan at 2.5%, followed by Kedah and Pahang at 2.3% each and Kuala Lumpur at 2.2%. Month-on-month headline inflation was unchanged in July, while food and beverages inflation increased 0.3%.

VIET NAM
Viet Nam accelerates preparations for 6G, including global standard-setting and domestic tech development
(17 August 2026) Viet Nam is accelerating preparations for 6G, with the Ministry of Science and Technology establishing a steering committee to support early participation in international standard-setting, domestic technology development and eventual deployment. The deputy director of the Vietnam Telecommunications Authority said it took Viet Nam more than eight years to master 4G technology and produce equipment after the 4G standards were issued, with this period shortened to about two years for 5G. By early 2026, Viet Nam had deployed more than 40,000 5G base stations covering 90% of the population, including about 250 stations using equipment designed and manufactured domestically. The government plans to increase the use of Vietnamese-made telecommunications equipment and raise the domestic share of research, development and technology products. Viettel has become the first global partner in Qualcomm Technologies’ 6G Early Access Program, with the companies targeting the first pre-commercial 6G call in early 2029 using Viettel-developed and manufactured systems and equipment. Under its digital infrastructure plan, Viet Nam aims for nationwide fibre-optic access at speeds of at least 1Gbps by 2030, 99% 5G population coverage and readiness to conduct 6G network trials.

VIET NAM, THE PHILIPPINES
Semiconductor boom pushes Viet Nam and the Philippines closer to ‘high-income’ status
(19 August 2026) Viet Nam and the Philippines entered the World Bank’s upper-middle-income category in July, with the next challenge being a shift from low-cost manufacturing towards higher-value industries. The World Bank defines the category as 2025 per-capita GNI of USD 4,636–USD 14,375, with Viet Nam and the Philippines approaching Indonesia in GNI. Viet Nam is expanding its semiconductor industry through foreign investment, including LG Innotek’s planned USD 1 billion semiconductor substrate plant, while Samsung Electronics and Intel are reportedly expanding or establishing facilities. Domestic firms Viettel and FPT are also considering semiconductor production, with Viet Nam targeting domestic capabilities spanning chip assembly, front-end processing, design and development. The government plans to train 50,000 semiconductor professionals by 2030 and upgrade related education, with former Prime Minister Pham Minh Chinh having stated in August 2025 that Viet Nam should be able to design, manufacture and test semiconductors by no later than 2027. The Philippines is upgrading its semiconductor sector, which is concentrated on back-end processes, and joined the US-led Pax Silica initiative in April; semiconductors and other electronics account for more than 50% of its goods exports by value.

CAMBODIA
Malaysia-Cambodia bilateral trade increases 51.1% year-on-year in first half of 2026
(17 August 2026) Malaysia-Cambodia bilateral trade increased 51.1% year-on-year to MYR 3.32 billion in the first half of 2026, while Malaysian exports to Cambodia rose 40.9% to MYR 2.45 billion, led by petroleum products, metal manufactures, textiles, apparel and footwear, chemicals and processed food. Matrade is leading 26 Malaysian companies on an Export Acceleration Mission to Phnom Penh from 18–21 August, covering food and beverages, fast-moving consumer goods, automotive parts and components, and lifestyle products. The CEO of Matrade said the delegation is nearly three times larger than the nine-company mission in 2025, which generated MYR 41.3 million in export sales through 104 B2B meetings, exceeding its MYR 34 million target. The 2026 mission is intended to secure new business opportunities, diversify export markets, and strengthen commercial links between Malaysian companies and Cambodian buyers, importers, and distributors. The mission includes a business seminar to be officiated by Cambodia’s Minister of Commerce, with speakers from the Ministry of Commerce, General Department of Customs and Excise, and Malaysian Business Chamber in Cambodia covering regulations, customs procedures, market trends and business opportunities. Participating companies will also hold pre-arranged B2B meetings and visit key commercial and distribution hubs in Phnom Penh.


RCEP Monitor


JAPAN
Real GDP expands 0.3% quarter-on-quarter in April-June quarter, marking third consecutive quarter of expansion
(16 August 2026) Japan’s real GDP grew 0.3% quarter-on-quarter in April-June, marking a third consecutive quarter of expansion but slowing from 0.5% in January-March and below economists’ expectations. Annualised growth was 1.1%. External demand contributed 0.5 percentage point to growth, mainly because imports fell as energy purchases from the Middle East declined, rather than because of stronger exports. Domestic demand weakened, with private consumption flat after rising 0.5% in the previous quarter and capital expenditure falling 1.2% following a 1.0% decline. Economists expect higher oil prices and inflation linked to the Middle East crisis to further pressure household and corporate budgets in the July-September quarter. The data has increased focus on whether the Bank of Japan will raise its 1% policy rate in September, with inflation risks heightened by yen weakness and higher crude prices. Market expectations for a September rate increase have risen despite the preliminary nature of the GDP data.

AUSTRALIA
Consumer sentiment rises 6.0% to 88.9 in August 2026 in consecutive monthly increase
(18 August 2026) Australian consumer sentiment rose 6.0% to 88.9 in August, marking a second consecutive monthly increase, although the index remained almost 10% below a year earlier and pessimists still outnumbered optimists. The Westpac-Melbourne Institute survey found sentiment improved sharply after the Reserve Bank of Australia kept its policy rate at 4.35% on 11 August, following three rate increases earlier in 2026. Responses collected after the decision produced an index of 91.1, compared with 83.6 before the meeting. Sentiment among mortgage holders increased 16%, while renter sentiment fell 2.3%. Measures of current financial and economic conditions improved more strongly than forward-looking assessments, with Westpac citing continued uncertainty, including regarding the Middle East. The index assessing whether it was a good time to buy major household items increased 8.1% to 93.8, but remained below its long-run average of 123.0. The index measuring whether it was a good time to buy a dwelling rose 12.1% to 95.7, its highest level since November 2025, but remained below the long-run average of 119.

NEW ZEALAND
Slowing population growth provides headwinds to post-oil shock economic growth
(18 August 2026) New Zealand’s population increased by 36,400, or 0.7%, to 5.36 million in the 12 months to June, with revisions reducing the estimated population by about 9,400 from previous estimates. Average annual population growth was about 33,300, the weakest rate since late 2013 outside the 2021–22 period when borders were largely closed. Net immigration contributed 17,600 people, the strongest quarterly result since late 2024 but still subdued partly because of continued departures of New Zealand citizens. Some 63,901 New Zealand citizens left the country in the 12 months to June, mainly seeking higher wages and employment opportunities overseas. Natural population growth slowed to 18,700, while births in the June quarter were the lowest since 2002. The annual fertility rate fell to 1.51 births per woman. Slower population growth is expected to limit demand for housing from both prospective buyers and tenants, while reducing a source of economic growth as the economy recovers from the global oil shock.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 762: Palm oil harvesting in Malaysia and Indonesia disrupted by higher fuel costs


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN
Palm oil harvesting in Malaysia and Indonesia disrupted by higher fuel costs
(07 August 2026) Palm oil harvesting in Malaysia’s Sabah and Sarawak states and Indonesia’s Sumatra is being disrupted by higher fuel costs and diesel supply shortages, reducing fruit collection and raising concerns over lower output. In Sabah and Sarawak, where 43.9% of Malaysia’s 20.28 million tonnes of crude palm oil output was produced in 2025, unsubsidised diesel prices have risen almost 120%, while the subsidised allocation of 200 litres per month remains below farmers’ estimated operational requirement of at least 500 litres. The Sarawak Dayak Oil Palm Planters Association said harvesting frequency has fallen from around 2.5 rounds per month to about 1.5 rounds, increasing the risk of abandoned fields and lower productivity. The association estimated harvesting delays could reduce Sarawak’s yields by 15% to 20%. Smallholders in Sabah and Sarawak also reported higher costs for transport, power generators and machinery, and called for revisions to diesel subsidy policies. In Indonesia, where Sumatra accounts for 55% of national palm oil output, diesel shortages since mid-July have disrupted fruit transportation, forcing farmers to extend harvesting intervals to eight to 12 days from the usual eight to 10 days. The disruptions coincide with palm oil futures rising more than 15% this year and concerns that an expected El Niño event later in 2026 could further reduce yields. Industry representatives warned that prolonged harvesting disruptions could weaken palm oil production in both countries.

VIET NAM
Government seeks 30% reduction in income tax for small firms and household businesses
(10 August 2026) Viet Nam’s government plans to seek parliamentary approval this month for a 30% reduction in income tax for household businesses, individual business operators and micro-enterprises with annual revenue of up to VND 10 billion (USD 380,000). The proposed measure would apply during 2026 and 2027. According to a government statement, the tax cut is intended to encourage household businesses, individual operators and small and medium-sized enterprises to expand production and business activities. The government said the proposal is part of efforts to support economic growth. The measure aligns with Viet Nam’s objective of achieving annual GDP growth of more than 10% for the remainder of the decade.

VIET NAM
Shein significantly scales back Viet Nam expansion plans due to changes in US trade policy
(10 August 2026) Shein has significantly scaled back its Viet Nam expansion plans, reducing its leased warehouse space near Ho Chi Minh City from 15 hectares to approximately 6 hectares, according to sources familiar with its operations. The bonded logistics hub, previously the largest of its kind in Viet Nam and employing thousands of workers, began mass layoffs in April, with some teams retaining only one-quarter of their staff. Sources indicated that only a third of the originally planned site is currently in use. The retrenchment follows changes in US trade policy, including the termination of the US de minimis duty-free exemption for shipments under USD 800 from all countries in 2025 and a reduction in the tariff advantage previously enjoyed by Vietnamese-made apparel over Chinese products. Additional US tariffs of 12.5% imposed last month on imports from both China and Viet Nam over alleged forced-labour compliance issues further weakened the rationale for relocating production to Viet Nam. Sources also cited operational challenges in Viet Nam, including lower labour efficiency and difficulties replicating Shein’s highly flexible Chinese supply chain. Several suppliers that had established operations in Viet Nam have reportedly returned production to China. Guangzhou authorities reportedly discouraged significant order transfers out of the region in mid-2025, while the chief executive of Shein pledged more than CNY 10 billion (USD 1.5 billion) in February to develop a smart supply-chain system in Guangdong. Shein’s draft prospectus showed a 14% decline in US revenue in the first quarter following the end of the de minimis exemption. Suppliers reported stagnant or only modest order growth, while some have shifted business to platforms such as Temu and Amazon or ceased working with Shein due to low margins and small order volumes.

THE PHILIPPINES
Philippines’ central bank prepared to tighten monetary policy further despite weak growth
(10 August 2026) Bangko Sentral ng Pilipinas (BSP) Governor Eli Remolona said the central bank is prepared to tighten monetary policy further, “as much as necessary”, to return inflation to its target level. Remolona stated that while the economy can withstand additional interest rate increases, weaker-than-expected economic growth in the second quarter has reduced pressure for further tightening. The BSP has already raised interest rates by 50 basis points this year and is scheduled to hold its next policy meeting on 27 August. Remolona reiterated that the BSP’s primary mandate is price stability, with economic growth viewed as a consequence of achieving that objective. He acknowledged short-term growth challenges but maintained the focus on reducing inflation. Although inflation eased further in July, it remains above the central bank’s 3% target for the year. The Deputy Governor of the BSP said core inflation, which excludes certain food and energy items, may have already plateaued. The Philippines recorded the weakest April–June economic growth among Southeast Asian economies that have reported second-quarter data. Elevated inflation and weak investment conditions continue to weigh on economic activity.

INDONESIA
Indonesia’s Consumer Confidence Index declines in July for third consecutive month
(10 August 2026) Indonesia’s Consumer Confidence Index declined to 116.8 in July from 117.8 in June, according to Bank Indonesia, marking a third consecutive monthly decline. The July reading was the lowest since September 2025, when the index stood at 115. This is the first instance of three successive monthly declines in consumer confidence since March 2025. Bank Indonesia did not specify reasons for the latest decrease but stated that consumer confidence in economic conditions remains stable. The central bank said consumer optimism continues to be supported by positive perceptions of current economic conditions and expectations for future economic conditions.

SINGAPORE
Government raises 2026 GDP growth forecast to 4.5% to 5.5%
(11 August 2026) Singapore’s Ministry of Trade and Industry raised its 2026 GDP growth forecast to 4.5–5.5% from 2–4% following stronger-than-expected first-half economic performance and a stronger global AI investment boom. Singapore’s economy grew 5.9% year-on-year in Q2 2026, slightly above the 5.7% advance estimate, while quarter-on-quarter growth reached 1.4%, bringing first-half GDP growth to 6.1%. Singapore’s Permanent Secretary for Trade and Industry said AI-related capital expenditure and demand had exceeded expectations and were supporting production and exports across technology-linked economies. Manufacturing expanded 12.5% year-on-year in Q2, driven by electronics and precision engineering demand linked to AI, while wholesale trade grew 8.3% and finance and insurance rose 6.2%, supported by stronger machinery and electronics sales, lending activity, fee income and fund management commissions. Chemicals and biomedical manufacturing recorded a second consecutive quarterly contraction, while food and beverage services declined due to higher outbound travel and lower visitor arrivals. The government said the impact of the Middle East conflict had been less severe than initially expected, although elevated energy and input costs are likely to persist through the remainder of 2026. Singapore does not currently expect significant effects from the 12.5% US tariff on exports, which affects about one-third of exports to the US, equivalent to approximately SGD 9.4 billion annually. Core inflation is expected to remain within 1.5–2.5%, with fuel, fertiliser and food prices posing greater inflation risks than AI-related investment. Maybank raised its 2026 GDP forecast to 5.2% from 4.8%, while UOB increased its forecast to 5.0% from 4.8%. RHB maintained a 4.5% forecast, citing risks from geopolitical tensions, US trade policy and a potential slowdown in AI-related investment.

THAILAND, MYANMAR
Thailand and Myanmar expanding energy cooperation, including in natural gas and petroleum
(11 August 2026) Thailand and Myanmar are expanding energy cooperation, including plans to extend natural gas supply contracts and explore investment in new petroleum resources, as Thailand seeks to diversify energy sources and reduce supply risks. Thailand’s Energy Minister and relevant agencies recently held discussions with Myanmar’s Union Minister for Electricity and Energy on natural gas exploration and production, gas trading and electricity-grid connectivity. The talks covered extensions of contracts for gas fields approaching the end of their current terms and potential investment in new resources, including the A6 field, which could supply gas to Thailand through existing pipeline infrastructure. A Thai government spokeswoman said Myanmar has been a key gas supplier to Thailand for nearly 40 years, with the Yadana and Zawtika fields previously meeting 15–20% of Thailand’s natural gas demand. Thailand and Myanmar are also expected to prepare a new memorandum of understanding on energy cooperation to provide a framework for future collaboration. The Thai government said the cooperation would strengthen energy security, provide additional supply options, reduce dependence on any single source and help manage electricity and production-cost risks that affect economic competitiveness. The Thai government also defended continued engagement with Myanmar, stating that bilateral relations involve security, economic, social and energy considerations.


RCEP Monitor


JAPAN
Listed Japanese firms’ net profits rise 68% year-on-year in April-June quarter
(11 August 2026) A Nikkei analysis of 956 Tokyo Stock Exchange Prime-listed companies showed combined consolidated net profit rose 68% year-on-year in the April–June 2026 quarter, the strongest increase since April–June 2021, with 70% of companies reporting higher profits. Aggregate revenue increased 14%, while net profit margin reached 9%, up 2.6 percentage points year-on-year and the highest quarterly level since the 2008 global financial crisis. Earnings were supported by a weaker yen, averaging around JPY 160 per US dollar during the quarter, approximately JPY 15 weaker than a year earlier, and by AI-related investment spending. Toyota Motor, Honda Motor and Suzuki Motor reported record April–June profits, supported by currency effects and stronger overseas hybrid vehicle sales. Combined net profit at six major semiconductor-related companies—Kioxia Holdings, Advantest, Tokyo Electron, Disco, Screen Holdings and Kokusai Electric—more than quadrupled to JPY 1.23 trillion, approaching Toyota’s JPY 1.47 trillion net profit. Murata Manufacturing’s net profit rose 60% due to growing demand for multilayer ceramic capacitors used in data centres. Panasonic Holdings reported a 90% increase in net profit, driven by energy storage systems and related products. Mitsui Kinzoku returned to profitability through sales of server-related copper foil, while Fanuc benefited from higher demand for numerical control devices used in data centres. Nissan Motor recorded its first quarterly net profit in two years following cost-cutting measures, including factory closures, alongside stronger sales in Japan and the US. Fujifilm Holdings is evaluating a partial spinoff of Fujifilm Business Innovation to reduce exposure to the mature printer market and focus on higher-margin businesses such as semiconductor materials. Companies face risks from potential yen appreciation following Japan-US market intervention, increasing competition from Chinese semiconductor manufacturers and the expansion of Chinese electric vehicle producers.

AUSTRALIA
Reserve Bank of Australia leaves official cash rate unchanged at 4.35%
(11 August 2026) The Reserve Bank of Australia (RBA) left its official cash rate unchanged at 4.35%, with all nine board members voting to maintain the current setting after three rate increases earlier in 2026. The RBA said financial conditions had tightened and economic activity appeared to be slowing as expected, but inflation remained above target and the board remained focused on preventing high inflation from becoming entrenched. The central bank expects inflation to return to around the midpoint of its target range only by late 2027 and warned of upside risks to that outlook. The RBA noted signs of slowing consumer spending, falling housing prices in some capital cities and a noticeable decline in new housing loans. Australia and New Zealand Banking Group forecast that capital-city house prices could fall by more than 10% during the current downturn. The RBA highlighted ongoing risks from the Middle East conflict, noting that oil and related commodity prices remain above pre-conflict levels and that some businesses are raising prices or considering price increases in response to higher costs. The bank said short-term inflation expectations had eased but remained higher than earlier in the year. BlackRock Australia said uncertainty surrounding the Middle East conflict and its potential inflationary effects remained significant and that BlackRock expects one additional interest-rate increase later in 2026 to address inflation risks and prevent higher inflation expectations from becoming embedded.

SOUTH KOREA
Seoul to establish five trillion won semiconductor fund to expand chip manufacturing capacity
(10 August 2026) South Korea will establish a five trillion won (USD 3.52 billion) semiconductor fund focused on promising chip materials, parts, equipment and fabless companies as part of efforts to expand national semiconductor manufacturing capacity. The Presidential Chief of Staff said the government will also provide an additional five trillion won in trade finance for suppliers and launch a 10-year, one trillion won programme to support collaboration between large companies and smaller suppliers in semiconductor development, testing and production. The measures form part of President Lee Jae Myung’s semiconductor megaproject initiative announced in June, under which Samsung Electronics, SK Hynix, suppliers and local governments are expected to invest more than USD 576 billion in new chip manufacturing projects. The government plans to seek parliamentary approval of a Mega Special Zone Act within 2026 to accelerate permits, environmental reviews and infrastructure development. Lee instructed the Defence Ministry to relocate functions of a military air base in Gwangju by mid-2028 to facilitate development of a semiconductor manufacturing complex on the site. The government has designated the 8.3 million-square-metre area as a candidate national industrial complex and aims to complete relocation and temporary dispersal of military facilities by the second half of 2028. Authorities plan to secure 650,000 metric tonnes of water per day for the Gwangju–South Jeolla semiconductor cluster by 2030 through recycled wastewater and nearby dams. For the Yongin semiconductor cluster, the government plans to provide 14.7 gigawatts of electricity by 2041 through cogeneration facilities, LNG generation and imported power from other regions. The administration said expanded semiconductor production is needed to meet growing artificial intelligence-driven demand beyond the capacity of existing Yongin and Pyeongtaek production bases.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 761: Southeast Asia’s manufacturing sector strengthens in July 2026


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN
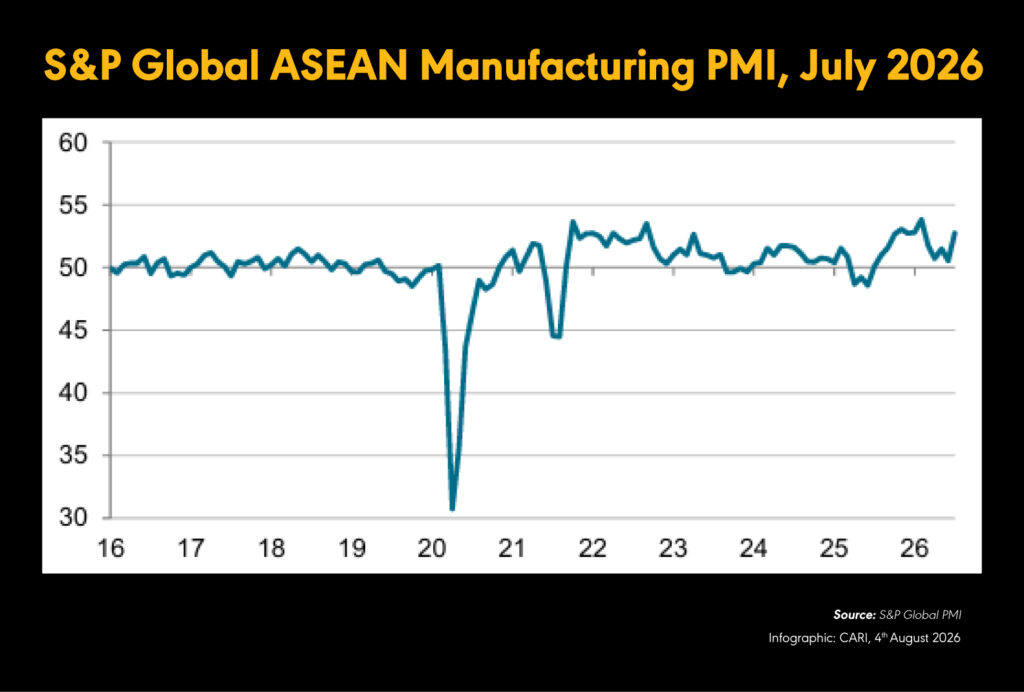
Southeast Asia’s manufacturing sector strengthens in July 2026
(03 August 2026) Southeast Asia’s manufacturing sector strengthened in July, with the S&P Global ASEAN Manufacturing PMI rising to 52.8 from 50.5 in June, the highest level since the Middle East conflict began and above the 50-point expansion threshold. Growth in new orders and production accelerated to their fastest pace since the start of the conflict, while firms increased purchasing activity and employment. Business confidence improved, with manufacturers reporting their strongest optimism for production growth in more than three years. Thailand recorded the highest PMI reading in the region at 54.2, followed by Vietnam at 52.9, while all ASEAN economies remained in expansionary territory except Myanmar, which registered 49.3. An economist for S&P Global Market Intelligence said the sector had moved beyond the weaker March–June period and returned to activity levels comparable with the start of the year, although still below February’s record high.

MALAYSIA
Malaysia assessing whether to lift moratorium on exports of unprocessed rare earths
(03 August 2026) Malaysia is assessing whether to partially lift its 2024 moratorium on exports of unprocessed rare earths as it seeks to strengthen its position in global critical minerals supply chains. Malaysia’s Deputy Minister of Natural Resources and Environmental Sustainability said pressure for policy changes is coming from Malaysian states and investors, with interest from the US, Australia, France and India. Any future exports would be subject to conditions including inbound investment commitments, technology transfers and use for research and development activities outside Malaysia. The deputy minister said Malaysia aims to become a regional critical minerals hub by 2030 and is seeking investment across the value chain, from mining to downstream processing. Malaysia holds 16.1 million tonnes of inferred rare earth reserves, previously valued by the government at MYR 970 billion, although much of the resource is located in protected forest areas. The government is mapping deposits and studying extraction methods that minimise biodiversity impacts. Malaysia’s recognised reserves account for around 1% of global reserves, compared with more than 50% for China, but the sector has attracted growing foreign interest. Australia’s Lynas Rare Earths, which operates a refining facility in Malaysia, has expressed interest in local deposits, while France’s Carester SAS plans a rare-earth separation plant in Perak through a venture with Malaco Mining Group. The deputy minister said Malaysia would continue engaging Chinese companies for potential technology sharing despite limited progress in expanding Chinese participation in the sector.

MALAYSIA
AI infrastructure boom sees more Malaysian companies in Forbes Asia’s 2026 Best Under A Billion list
(04 August 2026) Forbes Asia’s 2026 Best Under A Billion list includes 200 top-performing listed small and mid-sized companies across the Asia-Pacific region, with Malaysian representation more than doubling to 19 companies. Forbes Asia stated that more than half of the Malaysian firms on the list benefited from the country’s artificial intelligence infrastructure expansion. The publication noted that companies featured on the list have navigated geopolitical tensions and volatile energy markets, with many aligned to technology-related growth and the global AI boom. China had the highest number of companies on the list with 28, followed by India with 27. Malaysian cable manufacturer Southern Cable Group made its debut on the list, supported by demand from the data centre industry, which contributed 15% of its MYR 1.8 billion revenue in 2025. The ranking selected 200 companies from approximately 19,000 publicly listed firms in the Asia-Pacific region with annual sales between USD 10 million and USD 1 billion. Software companies and suppliers of semiconductor-related electronic components and tools accounted for 25% of qualifying firms. Forbes Asia also highlighted companies benefiting from growing adoption of electric vehicles and renewable energy through the provision of specialised equipment and services.

VIET NAM
Viet Nam records trade deficit of USD 3.59 billion in July 2026
(03 August 2026) Viet Nam recorded a trade deficit of USD 3.587 billion in July, widening from USD 2.64 billion in June, as imports continued to outpace export growth. July exports increased 25% year-on-year to USD 53 billion, while imports rose 41% to USD 56.67 billion. For January–July, exports grew 21.7% to USD 320 billion and imports surged 34.8% to USD 340 billion, resulting in a trade deficit of USD 20.5 billion, exceeding the previous full-year record deficit of about USD 18 billion in 2008. Foreign direct investment inflows during the first seven months of the year rose 11.8% year-on-year to USD 15.2 billion. Consumer price inflation eased to 4.45% in July from 4.69% in June, remaining close to the government’s 2026 target of 4.5%. Industrial production expanded 14.5% year-on-year in July, while retail sales also increased 14.5%. Higher fuel costs continued to contribute to import growth, with crude oil import volumes falling 11.9% but values rising 18%, while refined fuel imports increased 6% in volume and 67.6% in value. The data comes as Viet Nam pursues economic growth of more than 10% this year while facing a widening trade deficit, inflationary pressures and a new 12.5% US tariff imposed on 24 July under a Section 301 forced labour investigation, which Hanoi has rejected.

THAILAND
Thailand’s economic activity remains broadly stable in June 2026
(03 August 2026) Thailand’s economic activity remained broadly stable in June, with stronger private consumption and exports offsetting weaker manufacturing output and tourism-related services, according to the Bank of Thailand. Private consumption increased 1.1% month-on-month, supported by government measures and higher spending on consumer goods, while electric vehicle sales rose amid elevated fuel prices and increasing demand for green mobility. Private investment grew 0.5%, supported by higher exports of technology-related goods linked to the global electronics cycle and data centre investment. Manufacturing output declined due to reduced petroleum production during partial refinery maintenance shutdowns and lower production of non-electric vehicles. Tourism-related activity weakened as both tourism receipts and foreign visitor arrivals fell, particularly from short-haul markets, reflecting weaker demand and reduced flight services amid higher energy costs. The Assistant Governor of the Bank of Thailand said Thailand’s economy softened in the second quarter of 2026 compared with the previous quarter, largely because of higher energy prices and travel disruptions associated with the Middle East conflict. The central bank expects growth to continue, supported by exports, electronics-sector investment and government consumption-support measures. Key risks identified include geopolitical tensions, global trade policies, the recovery of the tourism sector, the impact of government policies and El Niño weather conditions.

THE PHILIPPINES
Lending growth among universal and commercial banks slows to 9.8% year-on-year in June 2026
(03 August 2026) Bank lending growth among Philippine universal and commercial banks slowed to 9.8% year-on-year in June 2026 from 12.1% in May, according to Bangko Sentral ng Pilipinas data. Business lending growth eased to 9.2% from 11.7%, reflecting more cautious corporate borrowing. Credit expansion remained concentrated in real estate, energy utilities, wholesale and retail trade, manufacturing, transport and agriculture. Overall growth was constrained by weaker borrowing in the construction, education and other services sectors. Consumer lending growth also moderated to 17.8% in June from 19.0% in May, driven by slower growth in credit card balances and motor vehicle loans. Total outstanding loans to resident corporate entities and individuals increased 10.3% year-on-year and continued to account for the majority of bank credit. The central bank said it would continue to align lending conditions with its mandate to maintain price and financial stability while monitoring credit growth as a key monetary policy transmission channel.

SINGAPORE
Singapore records 4,500 retrenchments in the April-June 2026 period
(03 August 2026) Singapore recorded 4,500 retrenchments in April–June 2026, up 17% from the previous quarter and the highest quarterly total in more than five years, according to preliminary Ministry of Manpower data. The increase was concentrated in outward-oriented sectors, particularly information and communications and manufacturing, and was mainly driven by business restructuring. The ministry said the rise remained below retrenchment levels seen during the 2009 Global Financial Crisis and the Covid-19 pandemic. Overall labour market conditions remained resilient, with employment increasing by 10,700 during the quarter and unemployment holding at around 2%. Singapore’s economy expanded 5.7% year-on-year in the second quarter, compared with 6.3% in the previous quarter, but remained above the government’s full-year forecast. Labour market sentiment improved in June, with 43.9% of surveyed firms expecting to increase headcount over the next three months, up from 40.6% in May. The proportion of firms planning wage increases rose to 29.3% from 23.7%, while those expecting layoffs fell to 2.7% from 3.2%. The ministry said the data indicated continued labour demand, although hiring and wage expectations remained below February levels and suggested businesses would adopt a cautious approach to workforce and pay decisions in the near term.


RCEP Monitor


SOUTH KOREA
Manufacturing sector expands at faster pace in July, rising to 53.1
(03 August 2026) South Korea’s manufacturing sector expanded at a faster pace in July, with the S&P Global Purchasing Managers’ Index rising to 53.1 from 52.1 in June and remaining in expansion territory for an eighth consecutive month. The survey showed stronger growth in both output and new orders during the month. New export orders increased for the first time in three months and recorded their fastest growth since April 2021. An economist for S&P Global said production volumes and new orders continued to rise, with particularly strong performance in the semiconductor and automotive sectors. The survey follows stronger-than-expected second-quarter economic growth, supported by a semiconductor export surge that offset weaker construction investment. Separate data released previously also showed factory output in June exceeded market expectations.

SOUTH KOREA
Consumer inflation slows to 2.8% year-on-year in July from 3.2% in June
(04 August 2026) South Korea’s consumer inflation slowed to 2.8% year-on-year in July from 3.2% in June, falling below 3% and undershooting the 3.0% median economist forecast. Core inflation, which excludes food and energy prices, edged up to 2.6%, indicating continued underlying price pressures despite the moderation in headline inflation. The Bank of Korea (BOK) said core inflation is likely to remain elevated as cost shocks continue to pass through and demand-side pressures strengthen. The data follows the BOK’s 25-basis-point interest rate increase to 2.75% last month, its first hike since January 2023. The Bank of Korea’s Governor stated that inflation is expected to remain above the central bank’s 2% target for an extended period and that future rate decisions will depend on inflation, growth and financial market conditions. Transportation costs led July’s inflation increase, rising 7.7% year-on-year, followed by recreation and culture at 5.5%, food and lodging at 2.8%, and household goods and services at 3.0%. Communication costs increased 0.7%, while food and non-alcoholic beverages rose 0.9%. The inflation data follows continued strong export growth, supported by semiconductor shipments linked to artificial intelligence demand. South Korea’s economy expanded 0.6% quarter-on-quarter in the second quarter, exceeding expectations, while the government maintained its forecast for 3% growth in 2026.

AUSTRALIA
Household spending rises to 0.8% month-on-month to AUD 81.3 billion in June 2026
(04 August 2026) Australian household spending rose 0.8% month-on-month to AUD 81.3 billion in June, exceeding expectations of a 0.2% increase and following a 1.2% rise in May, according to Australian Bureau of Statistics data. Annual spending growth accelerated to 6.0%, the highest level in three months. Real household spending increased 0.7% during the June quarter to AUD 227.8 billion. Transport spending was a key driver, with new vehicle sales contributing to a 3.0% increase in the category. The ABS said electric vehicle sales rose significantly over the year and continued to grow in June as households adjusted spending patterns in response to higher fuel prices. Air travel spending returned to levels seen before disruptions linked to the Middle East conflict began in March. Fuel spending volumes increased 7.8% in June as consumers took advantage of lower fuel prices. Recreation and culture spending rose 1.4%, supported by purchases of electronic goods, live entertainment and gambling activities associated with major sporting events. The data indicates continued strength in household demand despite the Reserve Bank of Australia raising interest rates three times this year to 4.35%.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 760: United States positioning itself as energy partner of choice for Southeast Asia


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN, UNITED STATES
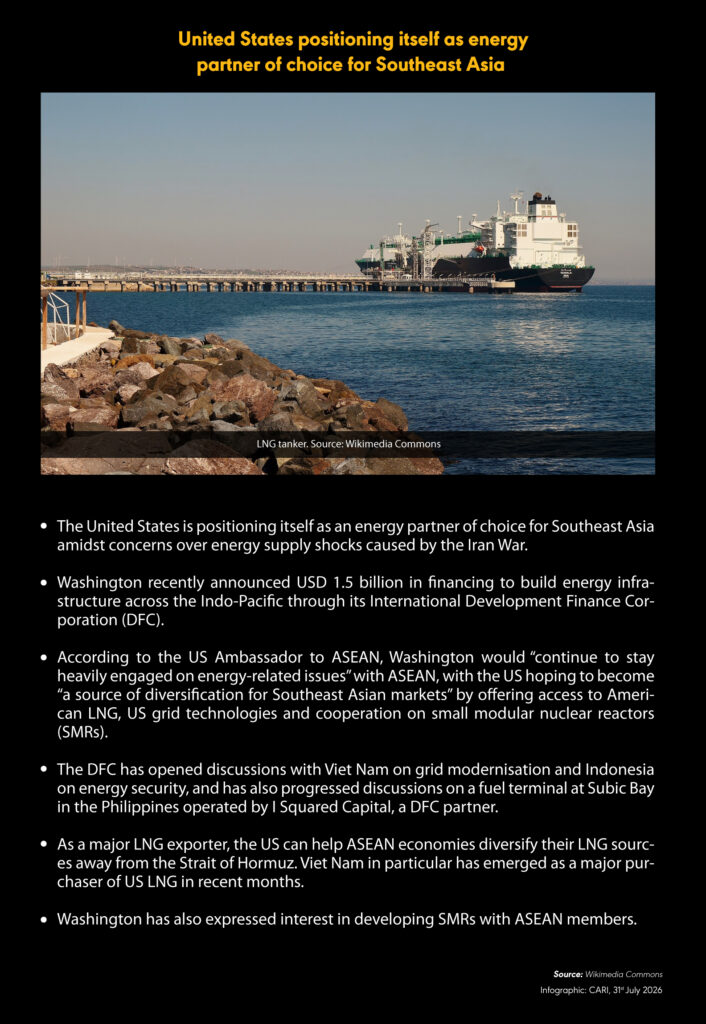
United States positioning itself as energy partner of choice for Southeast Asia
(29 July 2026) The United States announced a USD 1.5 billion financing commitment through the International Development Finance Corporation (DFC) on 22 July to support energy infrastructure across the Indo-Pacific, described as the largest project investment in the agency’s history. The announcement was made during US Secretary of State Marco Rubio’s visit to Manila for the ASEAN foreign ministers’ meeting, and was accompanied by a broader USD 2.5 billion investment commitment covering energy security and future technologies. The US Ambassador to ASEAN said Washington intends to expand engagement on energy security by offering US liquefied natural gas (LNG), grid technologies and cooperation on small modular nuclear reactors (SMRs), while supporting initiatives such as strategic petroleum reserves. Analysts said the funding is intended to mobilise private capital rather than provide direct grants to ASEAN governments and remains an investment platform rather than a portfolio of approved projects. Discussions have reportedly begun with Viet Nam on grid modernisation and Indonesia on energy security, while the Philippines is considered the most advanced potential project location through a fuel terminal at Subic Bay operated by DFC partner I Squared Capital. Analysts noted that the initiative could help diversify Southeast Asia’s energy sources and reduce exposure to supply disruptions, but cautioned that transmission constraints, regulatory uncertainty, project execution challenges and continued dependence on fossil fuels remain significant issues. The US is also promoting SMR cooperation with ASEAN governments, following a trilateral SMR agreement with Japan and South Korea earlier this month. Analysts highlighted potential applications for SMRs in Indonesia and the Philippines due to their dispersed island grids, and in Malaysia and Thailand to support growing data centre and artificial intelligence-related electricity demand. However, regulatory approvals, financing and public acceptance are expected to determine the pace of deployment.

ASEAN, UNITED STATES
US imposes new tariffs of 10-12.5% on seven ASEAN economies citing forced labour practises
(26 July 2026) The US imposed new Section 301 tariffs of 10-12.5% on 60 economies, including seven Southeast Asian countries, citing forced labour practices identified in recent investigations. Among ASEAN members, the Philippines, Singapore, Thailand and Viet Nam face the highest tariff rates, while Malaysia, Indonesia and Cambodia received lower rates after being assessed as having made greater enforcement efforts. The US Trade Representative said the measures were intended to address human rights abuses and trade distortions. The tariffs were announced one day after US Secretary of State Marco Rubio told ASEAN foreign ministers in Manila that the US was “with ASEAN 100 per cent”, prompting analysts to highlight a disconnect between US diplomatic messaging and trade actions. ASEAN governments, including the Philippines, Singapore and Indonesia, reiterated their opposition to forced labour and stated that they would continue engagement with Washington. Exemptions apply to semiconductor-related components and products already covered by existing tariffs, including automobile parts. Analysts said the measures are unlikely to trigger retaliation from ASEAN countries but may reinforce perceptions of the US as an unreliable economic partner. Economic impacts are expected to vary, with Viet Nam and Cambodia considered more exposed because exports to the US account for a larger share of GDP. Thailand could face greater pressure as key exports such as frozen seafood, rubber products and household appliances are not exempt. Despite the tariffs, analysts expect ASEAN countries to continue pursuing dialogue with the US, given its importance as a trade destination and source of foreign direct investment.

VIET NAM, UNITED STATES
US customs officials conduct spot checks at China-linked factories in Viet Nam over transshipment concerns
(28 July 2026) US customs officials have conducted spot inspections at China-linked factories in Viet Nam, reviewing documents, raw material sourcing, production processes and potential software intellectual property violations to assess the extent of value added before exports to the US. The inspections have heightened concerns that Washington could impose additional tariffs on Viet Nam, although officials have reportedly not found significant evidence of Chinese goods being illegally transshipped through the country. The inspections come as Viet Nam and the US continue difficult negotiations on a trade framework agreement reached in October, with disagreements centred on transshipment and other non-tariff barriers. Viet Nam has intensified efforts to address US concerns over trade fraud and intellectual property protection, including the seizure of 50,000 counterfeit Nike products and the submission of a 3,581-page report to the US Trade Representative detailing nearly 20,000 infringement cases handled between 2021 and 2025. Viet Nam is also facing three separate Section 301 investigations by the US, including probes into alleged intellectual property violations, excess manufacturing capacity, and allegations of forced labour in the supply chains. The US is seeking commitments beyond reducing the USD 178 billion bilateral trade gap, including stronger action on transshipment, economic security cooperation and intellectual property protection. Additional pressure emerged after Viet Nam was included among 60 economies subjected to new US tariffs over alleged shortcomings in preventing forced labour in supply chains, a claim rejected by Viet Nam’s foreign ministry.

VIET NAM
Viet Nam seeking USD 76 billion a year from capital markets to reduce reliance on banking
(29 July 2026) Viet Nam approved a comprehensive financial-market reform programme on 27 July, consolidating reforms across banking, equities, bonds, insurance and emerging financial products into a single framework extending to 2045. The programme aims to reduce reliance on bank lending by increasing capital-market fundraising to an average of VND 2 quadrillion (USD 75.95 billion) annually by 2030 and raising capital markets’ share of realised social investment to 30–35% between 2031 and 2045. Businesses are targeted to raise VND 5.4 quadrillion through the stock market during 2026–2030, while stock-market capitalisation is projected to reach 120% of GDP by 2045 from 82.3% at end-2025. Outstanding bond value is targeted to increase to 60% of GDP by 2030 from 30.7% in 2025. Planned measures include encouraging listings of foreign-invested companies, accelerating state divestments, introducing new derivatives products, launching a central counterparty clearing mechanism in 2027, piloting crypto-asset and carbon-credit markets, establishing a trading platform for innovative start-ups, and exploring a gold exchange and central bank digital currency. The programme also calls for full Basel III adoption, wider use of artificial intelligence in banking, expansion of insurance as a long-term funding source, and allowing insurers to invest in infrastructure bonds and real estate investment trusts. Bond issuance will be diversified through green, sustainability-linked and floating-rate instruments. By 2030, the government targets foreign investors’ capital-market assets at around 15% of GDP, stock investment fund assets at 5% of GDP, and pension fund assets to grow by an average of 11.5% annually between 2026 and 2030, alongside easier market access for foreign investors.

MALAYSIA
OECD encourages Malaysia to reintroduce GST and phase out fuel subsidies
(28 July 2026) The OECD’s latest Economic Survey of Malaysia recommends that Malaysia reintroduce the Goods and Services Tax (GST), broaden the personal income tax base, strengthen tax administration and gradually phase out fossil fuel subsidies to reinforce fiscal sustainability as the country approaches high-income status. The report recommends replacing broad energy subsidies with targeted cash transfers and adopting carbon pricing while using the government’s social registry to protect vulnerable households. The OECD said Malaysia’s tax revenue remains below 13% of GDP and that a broad-based consumption tax would provide a more stable revenue source to support higher spending on education, social protection, public investment and an ageing population. It projects Malaysia’s GDP growth at 4.9% in 2026 and 5.0% in 2027, with inflation at 2.1% this year, but warned that elevated public debt and gradual fiscal consolidation leave the country exposed to external shocks, including higher energy prices. The report also stated that although Malaysia is expected to attain high-income status between 2028 and 2030, fewer than half of Malaysians are likely to earn above the high-income threshold by then, with average household incomes needing to roughly double. It further highlighted slowing productivity growth, weaker education outcomes and underdeveloped social protection as priorities requiring structural policy reforms beyond sustaining economic growth.

THAILAND
Government plans to cancel proposed THB 1 trillion land-bridge project due to lack of economic viability
(24 July 2026) Thailand’s government plans to cancel its proposed THB 1 trillion (USD 29.7 billion) land-bridge project linking the Gulf of Thailand and the Andaman Sea after a government study concluded it is no longer economically viable and poses significant environmental risks. Thailand’s Finance Minister said a government committee has recommended terminating the project, with the updated assessment reversing an earlier study that had projected substantial economic benefits. The review lowered the project’s expected financial return to 4.8% from 8% and forecast cargo volumes up to 16% below previous estimates, while noting that nine of the world’s 10 largest shipping lines have already invested in competing projects, limiting commercial interest. The study also warned the project could harm environmentally sensitive areas, including Ranong’s biosphere reserve, wetlands and key marine tourism sites. Instead, the government plans to upgrade Ranong Port and develop a rail connection linking the Andaman coast to Thailand’s existing rail network to improve freight transport. The recommendation will be submitted to Prime Minister Anutin Charnvirakul and the Cabinet for approval. The minister said the government incurred no financial losses from the proposal because no land acquisitions had been made and construction had not commenced.

THE PHILIPPINES
Bangko Sentral ng Pilipinas conducts limited intervention in forex market to support peso
(28 July 2026) The governor of the Philippines’ central bank said the Bangko Sentral ng Pilipinas conducted limited intervention in the foreign exchange market last week to support the peso as it weakened to a record low. The governor stated that intervention was kept small and aimed only at maintaining orderly market conditions, noting that aggressively defending the currency against a strong US dollar would unnecessarily deplete foreign exchange reserves. The peso fell to an all-time low of 61.85 per US dollar and remained near that level as of Tuesday. The governor also said there is a small possibility of more aggressive monetary tightening if needed to return inflation to target. The central bank is monitoring the risk that peso weakness could contribute to higher domestic inflation.


RCEP Monitor


SOUTH KOREA
KOSPI index sees USD 2.18 trillion rout from peak reached just over a month ago
(29 July 2026) South Korean equities extended a sharp sell-off on 30 July, with the KOSPI falling as much as 12.6% intraday before closing 6% lower, following an almost 11% decline the previous day. The index has lost nearly 40% of its value from a peak reached just over a month ago, contributing to an estimated USD 2.18 trillion reduction in Seoul’s equity market value. The downturn was concentrated in AI- and semiconductor-related stocks and was amplified by leveraged retail positions being forcibly unwound by brokers. South Korea’s Finance Minister apologised for the introduction of single-stock leveraged ETFs and said the government is reviewing market stabilisation measures. Following a meeting involving the minister, the Bank of Korea governor and financial regulators, authorities announced plans for additional restrictions on single-stock leveraged products, including potential investment caps of up to 20% of an investor’s total portfolio, higher trading costs and simulated trading requirements. The government also said it would establish a legal basis for emergency market-stabilisation measures. SK Hynix reported a six-fold increase in profit, but its shares still fell 9.6%, while Samsung Electronics declined 5.2%; together the two companies account for more than half of the KOSPI’s market capitalisation.

AUSTRALIA
Inflation in June quarter undershoots forecasts, reducing expectations of interest rate hike next month
(29 July 2026) Australia’s consumer price index (CPI) rose 0.6% quarter-on-quarter in the June quarter, slowing from 1.4% in the previous quarter, while annual inflation eased to 4.0% from 4.1%, according to data from the Australian Bureau of Statistics. Core inflation, measured by the trimmed mean, increased 0.8% during the quarter, below market expectations of 0.9%, with the annual rate rising to 3.6% from 3.5%, but remaining below both market forecasts of 3.7% and the Reserve Bank of Australia’s forecast of 3.8%. Monthly CPI for June declined 0.1%, reducing annual inflation to 3.8%. The softer inflation data was partly driven by lower fuel costs and prompted markets to reduce expectations of an interest rate increase next month to 4%, down from 21% previously, while the probability of a rate hike later this year was priced at 40%. Following the release, the Australian dollar fell 0.4% to USD 0.6949 and three-year government bond yields declined 10 basis points to 4.479%. The Reserve Bank of Australia has raised its policy rate three times this year to 4.35%, and the bank’s governor stated that it remains unclear whether existing tightening is sufficient to return inflation to target. Labour market conditions remained resilient, with employment growth continuing in June despite a modest increase in the unemployment rate.

JAPAN
Japan to reduce 8% sales tax on food to 1% for two years from April 2027
(30 July 2026) Japanese Prime Minister Sanae Takaichi has instructed preparations to reduce Japan’s 8% sales tax on food to 1% for two years from April 2027, with the ruling Liberal Democratic Party beginning discussions to secure approval for the measure. The Secretary General of the LDP said the government intends to fund the tax cut without additional debt issuance, relying instead on higher-than-expected tax revenues. The government is expected to finalise the plan at a cabinet meeting in early August and submit related legislation during the autumn parliamentary session. The proposal would mark the first reduction in Japan’s consumption tax since its introduction in 1989. Takaichi opted for a reduction to 1% rather than a full suspension to avoid extensive modifications to retail cash register systems. The measure is intended as a temporary step before the introduction of a new payout programme targeted at low- and middle-income households. The announcement contributed to a 5.5 basis point rise in the 10-year Japanese government bond yield to 2.800%, reflecting investor concerns about fiscal pressures. Concerns remain over the impact on Japan’s public finances, with around one-quarter of the JPY 122 trillion (USD 746 billion) 2026 budget funded through debt issuance and consumption tax accounting for nearly 22% of revenue. Analysts also questioned the effectiveness of the tax cut in reducing household cost pressures and warned it could support higher inflation by boosting consumer purchasing power.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 759: Iran war and higher fuel prices reshaping tourism demand across Southeast Asia


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN
Iran war and higher fuel prices reshaping tourism demand across Southeast Asia
(07 July 2026) The Iran war and higher fuel prices are reshaping tourism demand across Southeast Asia, with travellers increasingly choosing shorter, lower-cost and more flexible regional trips over long-haul holidays. Bali resorts reported fewer European visitors and domestic Indonesian repeat guests, while arrivals from Malaysia, China and Singapore have increased. Indonesia’s foreign visitor arrivals rose 5.8% year-on-year in May despite weaker domestic demand. IATA forecasts average jet fuel prices of USD 152 per barrel in 2026, nearly 70% higher than a year earlier, although average weekly prices have fallen 20% over the past month, with Asia-Pacific airlines remaining exposed because of limited fuel hedging and reliance on Persian Gulf crude supplies. The Asian Development Bank said higher fuel costs are increasing expenses across airlines, hotels, restaurants, transport and tourism businesses. Malaysia’s weaker visitor growth in recent months has been attributed to higher airfares, flight disruptions linked to the Middle East conflict and softer long-haul demand rather than reduced competitiveness as a tourism destination, with BMI forecasting almost 28 million arrivals in 2026, about 5% above last year and above pre-pandemic levels. Tourism Malaysia reported demand remains resilient, with budget-conscious travellers booking later and taking shorter trips, while higher-income visitors continue to travel. Booking.com said Asia-Pacific travellers are prioritising flexibility, safety and value for money, with 93% of survey respondents citing safety and 91% value for money as key decision factors, while search data showed double-digit growth in interest for Da Nang, Nha Trang, Kuala Lumpur and Manila. Viet Nam recorded 12.3 million international visitors in the first six months of 2026, up 14.9% year-on-year, supported by stronger demand from China, South Korea and Japan, with resorts introducing new activities and reducing rates by 5% between July and September to attract visitors. Thailand’s foreign arrivals fell 2.3% year-on-year to 14.03 million in the first five months of 2026, prompting the Tourism Authority of Thailand to lower its full-year target to 30-34 million from 40 million and refocus marketing on short-haul visitors from China, Malaysia and India.

MALAYSIA
Exports rise 45.3% year-on-year to MYR 177.89 billion in June, fastest growth in nearly four years
(20 July 2026) Malaysia’s exports rose 45.4% year-on-year to MYR 177.89 billion in June, marking the fastest growth in nearly four years despite geopolitical tensions in the Middle East. This increase was below Bloomberg’s median forecast of 47.3% and followed May’s revised 44.7% growth. The Ministry of Investment, Trade and Industry said Malaysia’s trade has remained resilient despite ongoing geopolitical risks and expects several key products and export markets to achieve record highs this year, supported by electronics and demand from major trading partners. Electrical and electronic exports, which accounted for nearly half of total exports by value, increased 57% year-on-year. Petroleum product exports rose 56% while those of liquefied natural gas surged 83%. Exports to the United States more than doubled despite US tariffs, while exports to China rose 36% by value. Imports expanded 43.9% year-on-year to MYR 163.00 billion, driven by a 67% increase in capital goods imports, a 41.3% rise in intermediate goods and a 17.2% increase in consumption goods. Malaysia’s trade surplus widened 64.9% year-on-year to MYR 14.89 billion but declined 62.7% compared with May.

VIET NAM
Global automakers shifting production to Vietnam, but local value-add remains low
(18 July 2026) Honda will relocate production of its UC3 electric motorcycle from Thailand to its Phu Tho plant, with production scheduled to begin in September 2026, joining broader expansion plans by global automakers in Viet Nam. Toyota Vietnam plans to invest an additional USD 360 million to establish the country’s first hybrid vehicle production line, Honda aims to begin assembling hybrid cars in Vietnam in 2026, and SAIC Motor expects its proposed MG assembly plant to begin by the end of 2027. Viet Nam’s automotive market is projected to grow from approximately 630,000 vehicle sales and 484,500 domestically produced vehicles in 2025 to around 700,000 vehicle sales and 550,000 locally produced vehicles in 2026, while the Ministry of Industry and Trade forecasts annual demand of 1.0-1.1 million vehicles by 2030. During the first half of 2026, Toyota and Lexus sold 36,669 vehicles in Viet Nam, up 22% year-on-year, while Toyota Vietnam contributed more than USD 482 million in taxes and exported USD 37.2 million in auto parts. Industry observers said the expansion of vehicle manufacturing will create jobs, increase tax revenue and strengthen Viet Nam’s role in regional automotive supply chains. However, analysts said Thailand retains its position as Southeast Asia’s automotive manufacturing hub because of its mature supplier network, engineering capabilities and skilled workforce. The Vietnam Association for Supporting Industries said Viet Nam’s supporting industries remain underdeveloped, with many high-value components, including engines, transmissions, electronic systems and batteries, still imported, resulting in low localisation rates and higher production costs. Economists argue that Viet Nam has attracted major foreign automakers through land and tax incentives, but most value creation remains with foreign-owned brands, technologies and core components, while domestic firms continue to focus mainly on vehicle assembly. They argue that Viet Nam’s next priority is to strengthen domestic suppliers so they capture a larger share of the automotive value chain and secure longer-term benefits from foreign investment.

VIET NAM
Viet Nam’s pharmaceutical market projected to approach USD 10 billion in 2026
(20 July 2026) Viet Nam’s pharmaceutical market is projected to approach USD 10 billion in 2026, up from about USD 7 billion a few years earlier, driven by an ageing population, a growing middle class, rising healthcare demand and expanding health insurance coverage. Annual pharmaceutical spending has reached around USD 75 per capita, remaining below Thailand and Malaysia, indicating further growth potential. Foreign pharmaceutical companies are increasing investment through mergers and acquisitions, including Taisho’s acquisition of a controlling stake in DHG Pharmaceutical, Abbott Laboratories raising its ownership in Domesco to 51.7%, and Daewoong Pharmaceutical and Mirae Asset acquiring a 40.12% stake in Traphaco for more than VND 2.35 trillion. Analysts said overseas firms increasingly prefer acquisitions over building new factories to gain immediate access to Viet Nam’s manufacturing licences, distribution networks and customer base. SHS Research said the 2025-2030 period marks a new growth phase as the industry shifts towards internationally compliant manufacturing and deeper integration into global supply chains, while Viet Dragon Securities expects merger activity to accelerate among companies with strong hospital distribution networks, advanced production facilities and capacity for strategic foreign investment. Despite the positive outlook, domestic manufacturers remain dependent on imported pharmaceutical ingredients, with 80-90% sourced from overseas, and continue to face limited research and development capabilities.

THE PHILIPPINES
The Philippine Stock Exchange seeks to attract retail investors through reforms
(17 July 2026) The Philippine Stock Exchange (PSE) is introducing measures to increase retail investor participation, such as including a new trading engine later this year that will reduce the minimum trade size as well as introducing new exchange-traded funds. The bourse also seeks to allow faster stockbroker accreditation, allow margin trading, and offer derivatives targeted at institutional investors. The PSE President and CEO said the initiatives are intended to attract retail investors currently drawn to online gambling and cryptocurrency trading, as retail investors account for only 20% of equity trading compared with 80% in Viet Nam. The Philippines had 3.64 million stock market accounts in 2025, compared with around 10 million online gambling accounts. The Philippine Stock Exchange Index has rebounded 11% since its May low after the market was among the world’s weakest performers last year. The president of the bourse said the exchange is encouraging well-known companies to list to broaden retail participation, citing the planned fourth-quarter IPO of GCash owner Mynt Inc., which could raise a record PHP 92.3 billion (USD 1.5 billion), and the planned listing of motorcycle ride-hailing company Angkas. The PSE is also inviting Global Electric Transport, which operates electric minibuses in Manila, to pursue an IPO. PSE argues that attractive market valuations and competitive corporate profit margins provide a basis for improving investor confidence in the coming months.

INDONESIA
Bank Indonesia keeps 7-day reverse repurchase rate unchanged at 5.75%
(22 July 2026) Bank Indonesia kept its 7-day reverse repurchase rate unchanged at 5.75%, contrary to market expectations of a further increase following two consecutive rate hikes. The central bank also maintained the overnight deposit facility rate at 4.75% and the lending facility rate at 6.50%. Of 33 economists surveyed by Reuters, 20 had expected a further 25 basis point increase, while 13 correctly anticipated no change. Bank Indonesia has raised interest rates by a cumulative 100 basis points since May to attract foreign capital inflows and support the rupiah, which has faced pressure from concerns over Indonesia’s fiscal position, central bank independence and commodity export policies.

INDONESIA
Indonesia slashes 2026 budget for free meal programme to IDR 268 trillion
(22 July 2026) Indonesia has reduced the 2026 budget for President Prabowo Subianto’s free meal programme from IDR 268 trillion to IDR 229 trillion rupiah, following an earlier reduction from the original allocation of IDR 335 trillion. The secretary of the National Nutrition Agency said the revised figure is provisional, while a spokesperson stated that further cuts remain possible as the programme undergoes a one-month management review ordered by the president. The government confirmed the budget reduction will result in fewer beneficiaries, with the focus shifting from expanding coverage to improving quality, targeting recipients more effectively and preventing further food poisoning incidents. The programme currently serves 62.7 million recipients, although the number affected by the latest cuts was not disclosed. Previous cost-saving measures included suspending the programme during school holidays to save more than three trillion rupiah and reducing meal distribution from six days to five in March to save up to IDR 40 trillion amid the economic impact of the Middle East conflict. The head of the National Nutrition Agency announced her resignation for health reasons, while her predecessor and two former deputies have been accused of crimes related to the agency’s management. The programme was originally intended to reach at least 82.9 million children and pregnant or breastfeeding women.


RCEP Monitor


CHINA
GDP expands by 4.3% year-on-year in second quarter, marking weakest expansion in more than three years

(15 July 2026) China’s gross domestic product grew 4.3% year-on-year in the second quarter, slowing from 5.0% in the first quarter and marking its weakest expansion in more than three years, below the 4.6% consensus forecast. The slowdown reflected weak consumer spending, reduced government infrastructure investment and energy-related pressures despite lower-than-feared impacts from US-China trade tensions and the Iran conflict. Exports remained a key source of growth, rising 27% year-on-year in June after a 19.4% increase in May, while semiconductor exports surged 122% and industrial production grew 5.4% in the first half, easing from 6.1% in the first quarter. Retail sales increased 1.0% in June after a 0.6% decline in May, but auto sales fell 16.1% following a 16.0% drop in May as vehicle purchase subsidies were reduced. The property sector remained weak, with new home prices down 1.3% year-on-year in June despite a 0.1% monthly increase, while the urban unemployment rate improved marginally to 5.0% from 5.1% in May. Fixed-asset investment contracted 5.7% in the first half compared with 1.7% growth in the first quarter, and private investment declined 8.5%. Beijing maintained its full-year growth target of 4.5%-5.0% but is expected to increase fiscal spending on artificial intelligence, including data centres, as well as social security and healthcare rather than introduce broad-based stimulus. Analysts said stronger stimulus is unlikely unless exports weaken significantly or labour market pressures create broader social stability risks.

CHINA
Crude oil imports fall 41% year-on-year and 12% month-on-month in June
(14 July 2026) China’s crude oil imports fell 41% year-on-year and 12% month-on-month to 29.27 million tonnes in June, the lowest level since October 2016, reflecting the impact of the Persian Gulf conflict and weaker domestic demand. The renewed breakdown of the US-Iran truce has reduced prospects for a recovery in crude shipments through the Strait of Hormuz, which normally accounts for around half of China’s oil imports. Natural gas imports rose 3.7% year-on-year to a five-month high of 10.93 million tonnes as higher seaborne purchases offset lower domestic production and depleted storage despite reduced LNG shipments from the Middle East. Coal imports increased 30% to a five-month high of 42.78 million tonnes after tighter mine safety inspections following a fatal Shanxi mine accident curtailed domestic production, while record electricity demand and potential heatwaves could sustain import requirements. Fertiliser exports fell 48% year-on-year to 2.23 million tonnes, the lowest since April 2024, as China tightened export controls to preserve domestic supplies. Aluminium exports rose 45% to a record 711,000 tonnes, copper imports increased 3.1% to 478,000 tonnes, iron ore imports climbed 6.4% to a yearly high of 112.69 million tonnes, steel exports grew 6.6% to 10.32 million tonnes, and soybean imports rose 11% to a 13-month high of 13.55 million tonnes following increased shipments from Brazil and the US after the trade truce.

JAPAN
Japan’s electricity price rises to highest level since January 2023
(22 July 2026) Japan’s nationwide day-ahead spot electricity price rose to JPY 24.78 per kilowatt-hour on Wednesday, up 24% this week and the highest level since January 2023, driven by extreme heat, a weaker yen and higher fuel costs. Temperatures are expected to reach up to 40°C in parts of the Kanto, Chubu and Kansai regions, while Tokyo is forecast to record 36.8°C, more than 6°C above normal. Weather forecasts indicate the heat will ease briefly over the weekend before intensifying again across Kanto and Kansai into early August. Higher fuel costs have added to power price pressures, with the Japan-Korea Marker for spot liquefied natural gas rising to USD 21.61 per million British thermal units on Tuesday, its highest level since late March. The yen also weakened beyond 163 per US dollar for the first time since 1986, increasing the cost of imported gas and coal used for electricity generation. The government’s electricity subsidy programme, running from July to September, is expected to reduce the average household’s electricity costs by about JPY 5,000 over the three-month summer period compared with the previous year.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 758: Amazon’s model struggles to compete with local competitors in Southeast Asia


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


ASEAN
Amazon’s model struggles to compete with local competitors in Southeast Asia
(14 July 2026) Amazon has begun phasing out its Singapore fulfilment service from 06 July, including warehouse storage for retailers, while Amazon Fresh will cease operations and third-party sellers will also be affected. The company will retain its Singapore presence by focusing on cross-border shipments from its US, Japan and Germany stores, with Amazon Singapore citing continued demand for international products. Analysts attributed the retreat to Amazon’s centralised fulfilment model, which was considered costly and less suited to Southeast Asia than the localised logistics networks used by competitors such as Shopee, TikTok Shop and Lazada. Momentum Works said Amazon’s model struggled to adapt to regional market conditions, while Singapore’s relatively small e-commerce market and Amazon’s limited market share made the business difficult to sustain. Momentum Works estimated Singapore’s e-commerce gross merchandise value reached USD 5.9 billion in 2025, of which Amazon accounted for about USD 400 million, or 6%, while Amazon’s total Southeast Asian GMV was approximately USD 0.4 billion compared with Shopee’s USD 83.2 billion, TikTok’s USD 45.6 billion and Lazada’s USD 18 billion. Sea reported Shopee GMV of USD 37.3 billion in the January-March 2026 quarter, up 30% year on year, and reaffirmed guidance for approximately 25% annual GMV growth in 2026. TikTok Shop has expanded rapidly through livestream commerce and retail training programmes in Singapore, while Lazada has strengthened its position through local offerings such as RedMart. Amazon is increasingly positioning Southeast Asia as an export base rather than a consumer market, particularly by supporting Vietnamese SMEs to sell overseas, with the number of products sold by Vietnamese partners on Amazon increasing 35% in the 12 months to July 2025.

ASEAN
Malaysia leads Southeast Asia’s IPO market in first half of 2026
(13 July 2026) Deloitte reported that Malaysia led Southeast Asia’s IPO market in the first half of 2026 with 36 listings raising USD 1.3 billion, while Singapore recorded five IPOs raising USD 868 million. Across Southeast Asia, 47 IPOs raised more than USD 3.07 billion, down from 53 IPOs a year earlier, but total proceeds increased 117% from USD 1.41 billion as the average deal size rose from USD 26 million to USD 65 million. Deloitte said the market is shifting towards fewer but larger and more mature issuers. Three IPOs exceeding USD 500 million in proceeds—UI Boustead REIT in Singapore, Sunway Healthcare Holdings in Malaysia and Dien May Xanh Investment in Vietnam—collectively added approximately USD 8.93 billion in market capitalisation, whereas no IPO surpassed USD 500 million in the first half of 2025. Deloitte attributed Singapore’s improved performance to stronger investor confidence and support from recent capital market reforms, including the Monetary Authority of Singapore’s SGD 6.5 billion Equity Market Development Programme launched in February 2025. The report forecasts a healthy regional IPO market for the remainder of 2026, supported by a strong pipeline, improving investor sentiment and easing interest rates, although global macroeconomic uncertainty and valuation scrutiny remain risks. Deloitte Southeast Asia capital markets services leader Tay Hwee Ling said Malaysia is expected to maintain strong IPO momentum while Singapore should continue attracting sizeable institutional listings.

THAILAND
Thai stocks outperforming Southeast Asian peers as investors bet on political stability
(17 July 2026) Thailand’s benchmark SET Index has risen 30% in 2026, outperforming all Southeast Asian peers, as investors expect the government led by Prime Minister Anutin Charnvirakul to provide greater political stability following his party’s decisive February election victory. JPMorgan Asset Management recommended maintaining exposure to Thai equities, while a Bank of America survey indicated fund managers are reducing their underweight positions on Thailand. Foreign investors have made net purchases of almost USD 2 billion in Thai equities and USD 1.26 billion in bonds this year, reversing nearly USD 13 billion of equity outflows recorded over the previous three years. Improved sentiment has been supported by expectations of stronger foreign direct investment, increased participation in the global artificial intelligence supply chain, resilient exports, steady tourism and closer policy coordination between the government and central bank. Thailand has also benefited from portfolio reallocations away from Indonesia, where investors remain concerned about policy uncertainty. Earnings per share forecasts for the SET Index have increased 7% since Anutin’s election, while MSCI ASEAN earnings estimates have declined 1.9%. Official data showed foreign investment approvals increased 73% year on year to approximately THB 154 billion (USD 4.6 billion) in the first five months of 2026, reflecting faster approval processes and streamlined investment policies. Analysts cautioned that sustaining the market rally will depend on stronger corporate earnings and that risks remain from weak long-term economic growth, global headwinds, tourism uncertainty and the effects of El Niño.

MALAYSIA, INDONESIA
Malaysia emerges as fifth largest source of foreign investment into Indonesia in second quarter of 2026
(16 July 2026) Malaysia was the fifth-largest source of foreign investment into Indonesia in the second quarter of 2026, contributing USD 700 million, as Indonesia recorded total realised investment of IDR 511.8 trillion, up 7.1% year on year, creating 742,223 jobs, a 5.1% increase. Indonesia’s Investment and Downstreaming Minister said Hong Kong was the largest source of foreign investment in Q2 with USD 5.5 billion, followed by Singapore (USD 4.2 billion), China (USD 1.7 billion), Japan (USD 900 million) and Malaysia (USD 700 million), while noting that investments are recorded by the jurisdiction through which funds enter Indonesia rather than their ultimate origin. Total realised investment in the first half of 2026 reached IDR 1,010.6 trillion, up 7.2% year on year and equivalent to 49.5% of the annual target, generating 1,448,862 jobs, a 15% increase from a year earlier. Singapore remained Indonesia’s largest foreign investor in the first half with USD 8.8 billion, followed by Hong Kong (USD 7.8 billion), China (USD 3.9 billion), Japan (USD 1.9 billion) and the United States (USD 1.7 billion). The minister said the government continues to improve the investment climate through regulatory reforms, including Government Regulation No. 28 introduced in October, to provide greater certainty in licensing.

MALAYSIA, SINGAPORE
Johor Bahru-Singapore RTS Link to spur Singaporeans to spend USD 1.05 billion more in Johor Bahru
(16 July 2026) A joint study by the Singapore Business Federation, Restaurant Association of Singapore and Singapore Retailers Association projects that after the Johor Bahru–Singapore RTS Link begins operations in January 2027, Singaporeans will spend an additional USD 1.05 billion annually in Johor Bahru, around 40% more than the projected USD 756 million increase in spending by Johor Bahru visitors in Singapore. The study estimated that Singaporeans spent USD 1.7 billion in Johor Bahru in 2025, while Johor Bahru residents spent USD 1.3 billion in Singapore. Annual trips by Singapore consumers to Johor Bahru are forecast to increase 51%, with groceries, pharmaceuticals, dining and beauty products remaining the main spending categories. Among Johor Bahru respondents, 34% said they intend to visit Singapore after the RTS Link opens, while annual visits by public transport users are projected to increase 57%, with many motorists expected to switch to rail and spend more on overnight stays and entertainment. The study found that Singapore retail and food and beverage businesses expect stronger competition from Johor Bahru, particularly in price-sensitive sectors, while highlighting manpower shortages, compliance requirements and operating costs as barriers to improving competitiveness.

THAILAND
Number of beneficiaries under state welfare card programme reduced by 28%
(17 July 2026) Thailand has reduced the number of beneficiaries under its state welfare card programme by 28% to 9.5 million from 13.2 million in the 2022 registration round after the Ministry of Finance introduced stricter eligibility screening to better target low-income and vulnerable groups. The Fiscal Policy Office said eligible recipients now represent about 14% of the population, compared with the World Bank’s estimated poverty rate of around 12%. Of the 18.8 million people who registered for the 2026 programme, 5.76 million failed to meet existing eligibility criteria, while a further 3.56 million were excluded under new checks covering financial assets, company directorships, securities accounts, land ownership, credit cards and non-bank loans. The tighter screening is expected to reduce the fiscal burden by approximately THB 14.5 billion (USD 431.5 million). The changes come as Thailand’s public debt stood at 66.8% of GDP at the end of May, close to the government’s self-imposed ceiling of 70%. It has been noted that the revised recipient list reflects a more targeted approach to welfare distribution but remains above research estimates of 4 million to 5 million people in need, and called on Prime Minister Anutin Charnvirakul’s government to publish more data on recipient distribution to demonstrate that the reforms are intended to improve the fairness and efficiency of public spending rather than simply reduce expenditure.

SINGAPORE, TIMOR-LESTE
Global Group begins construction of first fuel storage terminal in Timor-Leste
(13 July 2026) Singapore-based Global Group has begun construction of its first fuel storage terminal in Timor-Leste, a USD 10 million project in Liquica expected to be completed within 10 months. The two-hectare facility will include two floating-roof tanks with storage capacity of 3.5 million litres of diesel and 2.5 million litres of petrol, with a second expansion phase planned for 2030. The terminal will support the company’s retail and wholesale fuel operations, which include nine petrol stations, fuel supplies for major construction projects and naval vessels, and a fleet of about 50 fuel trucks. The director of Global Group said the facility will strengthen inventory control, reduce reliance on third-party storage and eliminate annual throughput fees of approximately USD 1.8 million currently paid to Pertamina’s terminal. Global Group said its Timor-Leste operations generate annual turnover of USD 50-60 million and profits of USD 2-3 million, with wholesale fuel sales increasing from about 300,000 litres per month in 2014 to more than 3.5 million litres per month in 2024, supported by annual revenue growth of 8-10%. The company said it controls nearly two-thirds of Timor-Leste’s onshore fuel market and expects additional storage capacity will be required due to rising investor interest and economic development. Once completed, the terminal will become Timor-Leste’s third fuel storage facility and will reserve 150,000 litres of fuel for government use to enhance energy security. Global Group also reiterated its intention to pursue a public listing, after an earlier attempt to list its Timor-Leste unit on the Singapore Exchange’s Catalist board was unsuccessful because the market was considered too high risk, with Hong Kong identified as an alternative listing venue if required.


RCEP Monitor


SOUTH KOREA
Bank of Korea raises benchmark interest rate by 25 basis points to 2.75%
(16 July 2026) The Bank of Korea raised its benchmark interest rate by 25 basis points to 2.75% on 17 July, marking its first rate increase in more than three years and the first under Governor Shin Hyun-song, as it began a monetary tightening cycle to address inflationary pressures linked to the AI-driven semiconductor boom. The central bank had kept rates at 2.5% since May 2025 following its previous easing cycle. Shin said stronger domestic demand generated by the semiconductor boom is expected to sustain underlying inflationary pressures, and the bank will continue tightening until inflation returns to its 2% target. Consumer inflation accelerated to 3.2% year on year in June, the highest since December 2023, while the weak won, higher energy import costs, rising housing prices and elevated household debt also influenced the decision. The Bank of Korea noted that strong export demand for memory chips, sizeable bonus payments at Samsung Electronics and SK Hynix, and increasing household spending, wages and investment could further support inflation. South Korea’s exports rose 70.9% year on year in June, the fastest growth in nearly 50 years, while the government upgraded its 2026 GDP growth forecast to 3.0% from 2.0%, above the IMF’s 2.6% projection. Following the announcement, the Kospi Index fell more than 6%, while the won strengthened slightly to 1,484 per US dollar after having weakened 5% against the dollar year to date. Economists expect the Bank of Korea to raise rates by another 25 basis points in October, followed by two further increases in 2027, potentially lifting the policy rate to 3.5% by the first half of 2027.

CHINA, VIET NAM
China surpasses United States into becoming Vietnam’s largest seafood export market
(17 July 2026) China ha surpassed the United States into becaming Vietnam’s largest seafood export market in the first half of 2026, with imports of nearly USD 1.4 billion, up about 40% year on year, according to the Ministry of Agriculture and Environment. Exports to the United States totalled nearly USD 898 million, down about 1%, while Japan ranked third with nearly USD 788 million, up 2%. Nam Viet Corp said the shift towards China has become more pronounced since the start of the year as its proximity offers lower logistics costs, reduced shipping times and faster capital recovery amid persistently high freight costs to more distant markets. The Vietnam Association of Seafood Exporters and Producers (VASEP) said exporters have increasingly redirected shipments to China because of rising trade barriers in the United States and Europe. Exports to the United States continue to face stricter requirements under the Marine Mammal Protection Act, including additional Certificates of Admissibility for products such as tuna, while shrimp exports remain affected by high anti-dumping duties. VASEP added that higher shipments to the United States ahead of new tariff measures also increased inventories. The association said overall export growth reflected recovering demand and exporters’ ability to diversify markets and restructure products as buyers impose stricter pricing, quality, certification and traceability requirements.

JAPAN
Nationwide core consumer price index forecast to increase by 1.6% year-on-year in June
(17 July 2026) A Reuters poll of 16 economists forecasts that Japan’s nationwide core consumer price index, which excludes fresh food but includes energy, increased 1.6% year on year in June, up from 1.4% in May but remaining below the Bank of Japan’s 2% inflation target for a fifth consecutive month. Economists attributed the expected increase to higher energy prices linked to the Middle East conflict and revisions to medical service fees, despite continued easing in food inflation excluding fresh food. Mitsubishi UFJ Research & Consulting said rising crude oil prices associated with the Iran situation have reduced the decline in energy prices, while Mizuho Securities said the impact of revised medical fees and the Iran conflict is likely to become more evident during the summer. The inflation data will be considered by the Bank of Japan at its upcoming policy meeting alongside its quarterly review of economic growth and inflation forecasts. Japan’s wholesale inflation accelerated to 7.1% year on year in June, the fastest pace since March 2023, reinforcing expectations that the central bank may continue raising interest rates. Official consumer inflation data will be released on 24 July.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 757: World Bank upgrades Viet Nam and the Philippines to upper-middle-income status


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


VIET NAM, THE PHILIPPINES
World Bank upgrades Viet Nam and the Philippines to upper-middle-income status
(02 July 2026) The World Bank reclassified Viet Nam and the Philippines as upper-middle-income economies on 01 July after their 2025 gross national income per capita reached USD 4,970 and USD 4,850 respectively, exceeding the USD 4,636 threshold. Viet Nam had been classified as lower-middle-income since 2009, while the Philippines had remained in that category since the late 1980s. The World Bank attributed Viet Nam’s upgrade to its export-led growth model and the Philippines’ to broad-based economic expansion across major industries. The reclassification means all five major Southeast Asian economies – Singapore, Malaysia, Thailand, Viet Nam and the Philippines – are now in the upper-middle-income tier or higher. The Philippines’ Economic Planning Secretary said the upgrade reflected sustained inclusive growth, stronger economic fundamentals and continued progress on the country’s development agenda despite global and domestic shocks. Viet Nam is targeting annual double-digit economic growth in 2026, supported by business-friendly reforms and large-scale infrastructure investment. The higher income classification may reduce access to concessional development financing, including below-market-rate loans used by the Philippines for infrastructure, disaster recovery and social programmes. The Union Bank of the Philippines said the upgrade indicates greater economic self-sufficiency, while the Philippines’ Economic Planning Secretary said any decline in concessional official development assistance should be offset by stronger fundamentals and improved market access, although income disparities and economic challenges remain.

VIET NAM
Viet Nam considering expanding coal-fired power generation due to LNG supply disruptions
(08 July 2026) Viet Nam is considering expanding coal-fired power generation as part of revisions to its national power development plan to strengthen energy security following disruptions to liquefied natural gas (LNG) supplies caused by the US-Iran conflict. In a 07 July statement, the Ministry of Industry and Trade said recent Middle East conflicts had affected LNG supply and proposed adding alternative electricity sources, including coal-fired capacity on an appropriate scale. Viet Nam had planned for LNG to account for up to 12% of its power mix by 2030, but the country, which began importing LNG only in 2023, currently relies on the spot market where prices are about 70% higher than pre-war levels. LNG deliveries through the Strait of Hormuz, which previously handled around one-fifth of global LNG shipments, have remained vulnerable despite an interim peace agreement, with recent attacks including one on a Qatari LNG tanker. The supply disruptions are prompting several Asian countries to diversify their energy sources, with some increasing coal use while others accelerate renewable energy development. Coal remains Viet Nam’s dominant power source, accounting for more than half of electricity generation in the first half of the year, according to state-owned utility EVN.

MALAYSIA
Analysts expect ringgit to recover due to central bank measures and strong economic fundamentals
(06 July 2026) Analysts expect the ringgit to recover after ending June as Asia’s weakest-performing currency, supported by Bank Negara Malaysia’s (BNM) measures to increase foreign-exchange inflows and the country’s strong economic fundamentals. Royal Bank of Canada forecasts the ringgit to strengthen to MYR 3.95 per US dollar by year-end, while Australia & New Zealand Banking Group projects MYR 3.80, its strongest level since 2015. The ringgit closed 0.2% higher at 4.0722 per US dollar on Friday and has outperformed all Asian currencies since BNM announced on 24 June that it would intensify efforts to encourage the repatriation and conversion of companies’ overseas earnings. RBC said Malaysia’s solid trade surplus, sustained inflows into ringgit-denominated debt and measures to increase conversion of foreign earnings should support further currency appreciation. Malaysia’s exports rose 45% year on year in May, lifting the monthly trade surplus to a record MYR 40 billion (USD 9.8 billion), while demand linked to artificial intelligence, data centres and electrical and electronic products continued to support the economy. BNM data showed foreign investors purchased about USD 2.1 billion of Malaysian bonds through 29 June, putting the market on course for its largest monthly inflow since May 2025. Analysts noted that a more hawkish US Federal Reserve and domestic political uncertainty, including upcoming state elections testing support for Prime Minister Anwar Ibrahim’s ruling coalition, remain key risks to the currency’s outlook.

INDONESIA
S&P Dow Jones Indices places Indonesia on watchlist for possible downgrade
(08 July 2026) S&P Dow Jones Indices (S&P DJI) has placed Indonesia on a watchlist for a possible downgrade from emerging to frontier market status in its 2027 review, citing concerns over stock ownership transparency and warning that special treatment for Indonesian securities could be introduced if conditions deteriorate. S&P DJI said Indonesia’s market classification would be reassessed at the next annual review if these concerns remain unresolved for one year after any special measures are implemented. The announcement follows MSCI’s ongoing review of Indonesia’s emerging market status, with a decision expected in November. Since MSCI raised similar concerns in January over concentrated and opaque ownership structures affecting price formation, the Jakarta Composite Index has fallen 31% this year and declined a further 1% on Wednesday. Indonesian authorities have responded by doubling the minimum free float requirement to 15%, with companies given up to three years to comply, and lowering the shareholder disclosure threshold from 5% to 1%. Allspring Global Investments said investors are likely to remain cautious until the reforms are fully implemented and shown to address the concerns of major index providers. Investor sentiment has also been affected by concerns over President Prabowo Subianto’s fiscal policies and increased state intervention in the private sector. The rupiah has depreciated 8% against the US dollar this year and is trading at record lows.

INDONESIA, CANADA
Canada-Indonesia trade remains below potential despite approaching USD 7 billion annually
(10 July 2026) The Canadian Ambassador to Indonesia said trade between the two countries remains below its potential despite approaching USD 7 billion annually, with the newly signed Indonesia-Canada Comprehensive Economic Partnership Agreement (ICA-CEPA) expected to expand trade and investment. Canada completed ratification of the agreement in May, while Indonesia is expected to ratify it in the coming months through a presidential regulation. Under the agreement, Indonesia will eliminate or reduce tariffs on 85.9% of its tariff lines for Canadian goods, while Canada will remove duties on 90.5% of its tariff lines. Indonesia recorded approximately USD 4.4 billion in bilateral trade with Canada in 2025, comprising nearly USD 1.7 billion in exports, led by electrical machinery and equipment, and almost USD 2.7 billion in imports. The Canadian ambassador identified opportunities for Indonesian exporters in agriculture, textiles, manufacturing, fabrics, sustainable forestry, furniture and small and medium-sized enterprise products, while highlighting energy, clean technology and aerospace as key sectors for Canadian companies in Indonesia. He said the agreement also provides greater regulatory certainty for businesses and investors through provisions covering critical minerals, SMEs, agricultural protocols and sanitary and phytosanitary dialogue. The ambassador noted growing opportunities for Indonesian investment in Canada, including interest in potash mining and Royal Golden Eagle’s existing investment in a liquefied natural gas project in British Columbia, with expansion under discussion. He added that both countries aim to significantly increase bilateral trade and investment over the next decade, with artificial intelligence and clean technology expected to become important areas of future economic cooperation.

THAILAND
Board of Investment approves nine investment projects worth THB 66.3 billion
(08 July 2026) Thailand’s Board of Investment (BOI) has approved nine investment projects worth 66.3 billion (USD 1.99 billion) across artificial intelligence, advanced electronics, aviation, clean energy and food sectors. The secretary general of the BOI said the projects demonstrate continued multinational investment in Thailand’s industrial and technology capabilities. The BOI has expanded its energy panel into the Subcommittee on Energy Management for Data Center Investment and Project Screening, chaired by the Energy Minister, to assess data centre projects on resource use, environmental impact and clean energy sourcing before tax incentives are granted. Japan’s Datasection (Thailand) will invest THB 7.8 billion (USD 235.2 million) in GPU server infrastructure in Bangkok and Pathum Thani. South Korea’s Doosan Electro-Materials (Thailand) will invest THB 6 billion (USD 180.2 million) in Samut Prakan to produce copper-clad laminate and prepreg for printed circuit boards, while Taiwan Union Technology (Thailand) will invest THB 6.3 billion (USD 189.2 million) in Chonburi to manufacture similar materials for AI servers and data centres. Fulltech Fiber Glass (Thailand) will invest THB 3.3 billion (USD 99.4 million) in Chachoengsao to produce specialised glass fibre fabric for PCB manufacturing. Nestlé (Thai) will invest THB 22.9 billion (USD 688.7 million) to expand coffee production in Samut Prakan for domestic and regional markets. Thai Airways International received approval for two projects worth THB 14.3 billion (USD 430.2 million) to lease eight passenger aircraft for its international network. Lomrak Green Energy will invest THB 5.6 billion (USD 168.7 million) in two wind power projects in Lopburi with a combined capacity of 120MW. The government also announced a seven-point energy action plan, including a dedicated electricity tariff for data centres, expanded clean power trading, accelerated grid investment and measures to support future large-scale digital infrastructure projects.

SINGAPORE
Temasek Holdings to increase AI-related exposure two-fold over next five years
(08 July 2026) Temasek Holdings plans to increase its artificial intelligence (AI)-related exposure from 6% of its portfolio at end-March to as much as 15% by 2031, focusing on energy and data centres, semiconductors, cloud services, foundation models, and AI software and applications. The state investor reported that the net value of its portfolio exceeded SGD 400 billion for the first time, rising from SGD 350 billion a year earlier. The CEO of Global Investments said Temasek will expand its AI investments in a disciplined manner while managing overall portfolio risk and expects long-term returns despite potential market volatility and overvaluation. Temasek’s existing AI investments include OpenAI, Anthropic, Nvidia, SK Hynix and Samsung Electronics. The firm also sees opportunities in China, particularly in AI, robotics and advanced manufacturing, with its China exposure increasing to 17% from 16% a year earlier, while exposure to the Americas rose to 26% from 25%. Temasek’s Chief Investment Officer said geopolitical risks are a key consideration in investment decisions. During the financial year, Temasek invested SGD 39 billion and divested SGD 24 billion, while reporting annualised returns of 8% over 20 years and 7.5% over 10 years. The investor also plans to increase infrastructure exposure, including renewable energy, nuclear energy, decarbonisation technology and grid modernisation, from 1% to 5% by 2031, and expand private credit exposure from 2% to 5%, with a focus on senior secured lending and diversified credit strategies.


RCEP Monitor


AUSTRALIA
Australia to export uranium to India for civilian nuclear programme
(09 July 2026) Australia and India have signed an administrative arrangement enabling Australian uranium exports for India’s civilian nuclear power programme, marking the completion of more than a decade of negotiations following their 2014 nuclear cooperation agreement. Australian Prime Minister Anthony Albanese said the agreement will support India’s expansion of non-fossil fuel power generation while creating an additional export market for Australia’s resources sector. Indian Prime Minister Narendra Modi said the deal will facilitate uranium supplies from Australia and support India’s clean energy objectives, with both countries also planning to develop a critical minerals corridor. India aims to expand its nuclear power generation capacity more than tenfold to 100GW by 2047 and is increasing uranium imports due to constraints on domestic production. India currently imports uranium from Russia and Uzbekistan, while supplies from Canada’s Cameco are scheduled to begin next year under an agreement signed in March. The agreement did not disclose the volume or duration of uranium exports. Australia holds the world’s largest uranium reserves and is the fourth-largest producer, with uranium exports worth AUD 1.6 billion (USD 1.1 billion) in the 2025–2026 financial year. BHP, Australia’s largest uranium oxide producer through its Olympic Dam operations, said demand from India for minerals including uranium is expected to grow, noting that India is already one of its largest customer markets globally. Spot uranium prices have traded at around USD 85 per pound this year after briefly reaching USD 94 in February.

SOUTH KOREA
South Korean equities enter technical bear market on uncertainty over chipmakers
(08 July 2026) South Korean equities have entered a technical bear market, with the Kospi Index falling more than 20% from its June record high after declining over 5% on Wednesday. Despite the correction, the Kospi remains the world’s best-performing major stock index this year, having gained more than 70% in local currency terms. Samsung Electronics and SK Hynix, the market’s two largest constituents, fell 6.3% and 5.7% respectively on Wednesday, following a decline of as much as 10% in Samsung shares on Tuesday despite the company forecasting a third consecutive quarter of record operating profit. Analysts attributed the decline to uncertainty over whether South Korean chipmakers can secure long-term customer purchase agreements similar to those adopted by US competitor Micron, raising concerns about the sustainability of AI-driven earnings. BNP Paribas said greater clarity on long-term contracts could support higher valuations for Korean semiconductor companies. South Korea’s financial regulator also warned of excessive leveraged stock investments by retail investors, with leveraged exchange-traded funds contributing to heightened market volatility. Some fund managers described the decline as a necessary correction after a rapid rally and said it could create investment opportunities beyond AI-related stocks. The market correction comes shortly before SK Hynix’s planned US share listing through a USD 29 billion offering, expected to be the largest share issuance by an Asian company.

CHINA
China’s consumer price index rises 1.0% year-on-year in June in slowdown from May
(08 July 2026) China’s consumer price index (CPI) rose 1.0% year on year in June, below the 1.1% forecast in a Reuters poll and slower than May’s 1.2% increase, reflecting continued weak domestic demand. Core CPI also eased to 1.0% from 1.1%, while food prices fell 1.6% year on year after a 1.7% decline in May. The producer price index (PPI) increased 4.1% year on year, matching forecasts and accelerating from 3.9% in May to its strongest growth since July 2022, although it declined 0.3% month on month. The Economist Intelligence Unit attributed the annual increase partly to a low comparison base and said manufacturers were unable to fully pass higher costs on to customers because of subdued demand. Higher commodity prices linked to the Middle East conflict and increased demand for artificial intelligence-related technology, including semiconductors and computing equipment, continued to support wholesale prices and manufacturing activity. Analysts said China’s economy remains characterised by strong exports and manufacturing alongside weak household consumption and a subdued property market. Teneo said policymakers are unlikely to introduce significant additional stimulus unless the slowdown persists, with the Communist Party Politburo meeting in late July viewed as the next opportunity for policy adjustments. The International Monetary Fund raised its 2026 China growth forecast to 4.6% from 4.4%, citing resilient high-tech manufacturing, exports and front-loaded public infrastructure investment, while China maintains a growth target of 4.5% to 5%.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)

CARI Captures Issue 756: Three biggest foreign banks in Indonesia remit USD 640 million from country


Captures has widened its scope to include news related to all the members of the Regional Comprehensive Economic Partnership (RCEP) agreement which was signed towards the end of 2020. Besides the ASEAN Member States, this includes Australia, New Zealand, China, Japan, and South Korea. The other weekly newsletters under CARI, China-ASEAN Monitor and Mekong Monitor will also be consolidated into the Captures newsletter. We hope this new version of Captures will serve you better and look forward to providing a curation of stories relevant to ASEAN and its trading partners.


INDONESIA
Three biggest foreign banks in Indonesia remit USD 640 million from country
(29 June 2026) The Indonesian units of Citigroup, Standard Chartered and HSBC remitted a combined IDR 11.5 trillion (USD 640 million) to their parent companies during 2024-2025, slightly exceeding their combined profits over the period. The remittance ratios were above historical averages, with Citigroup transferring nearly all of its combined 2024-2025 earnings, Standard Chartered remitting more than IDR 1.1 trillion in 2024, equivalent to almost four times its annual profit, and HSBC sending almost IDR 3 trillion in 2025 despite recording less than IDR 2.2 trillion in net income. According to bankers cited in the report, the higher remittances reflect reduced exposure to Indonesia amid concerns over President Prabowo Subianto’s increasingly state-focused economic policies, market volatility and pressure to support government priorities. Danantara, the state sovereign wealth fund overseeing assets valued at about USD 900 billion, reportedly sought commitments of up to USD 1 billion from each of 10 banks for a proposed USD 10 billion loan facility. The report also cited concerns over discussions on expanding banks’ role in financing government programmes, although Indonesia’s Financial Services Authority (OJK) stated that lending decisions remain based on banks’ commercial judgement and that it does not intervene. The increased profit repatriation coincides with earlier reductions in Indonesian operations by the three banks, including Citigroup’s 2022 sale of its retail banking business, Standard Chartered’s 2023 divestment of a retail loan portfolio, and HSBC’s planned sale of its retail and wealth assets. Analysts also said the weaker rupiah has reduced the attractiveness of retaining earnings in Indonesia.

THE PHILIPPINES, CHINA
The Philippines courts Chinese investors from the Greater Bay Area
(30 June 2026) The Philippines’ Trade Secretary said at the South China Morning Post’s GBA-Asean Summit 2026 in Hong Kong that the Philippines is positioning itself as a gateway for Greater Bay Area businesses expanding into Southeast Asia, highlighting its strategic location, young English-speaking population of around 115 million, and digitally skilled workforce. She said the country could complement the Greater Bay Area’s research and development capabilities while providing a platform for regional expansion. As 2026 ASEAN chair, the Philippines is promoting stronger ASEAN-Hong Kong economic ties, with the ASEAN Digital Economy Framework Agreement completed in May and targeted for signing by November to support partnerships in e-commerce and digital innovation. The Secretary cited a 15.4% increase in Philippine exports in 2025 as evidence of strong demand for the country’s goods. She identified semiconductors, electronics, manufacturing services, renewable energy and agricultural exports including coconuts, pineapples, bananas, ube and kalamansi as priority sectors for collaboration with Hong Kong. The Philippine Economic Zone Authority approved PHP 140.7 billion (USD 2.3 billion) of investments in the first half of 2026, representing a 94% year-on-year increase. The Secretary noted that China remains the Philippines’ largest trading partner, with bilateral trade reaching USD 7.72 billion in April, comprising USD 5.69 billion of Chinese exports to the Philippines and USD 2.03 billion of Philippine exports to China.

THE PHILIPPINES
The Philippines approves record 12% minimum wage increase for more than 1.1 million workers
(30 June 2026) The Philippines approved a record 12% minimum wage increase for more than 1.1 million workers in Metro Manila, with the Labour Secretary stating that the adjustment will take effect in two stages: PHP 60 per day from 19 July and a further PHP 25 in January 2027. Once fully implemented, the daily minimum wage for non-agriculture workers will rise by PHP 85 to PHP 780, while wages for agriculture, service and retail establishments employing 15 workers or fewer, and manufacturing establishments with fewer than 10 workers, will increase by 13% to PHP 743 per day. The Department of Labour described the increase as the largest single wage adjustment ever granted in the capital region. The Trade Union Congress of the Philippines criticized the increase as insufficient and opposed its phased implementation, citing a decline in workers’ purchasing power. The wage adjustment follows inflation easing to 6.8% in May from a three-year high of 7.2% in April, although inflation remains above the central bank’s 4% tolerance ceiling.

MALAYSIA
Malaysia’s headline inflation increases to 2.0% in May 2026 from 1.9% in April
(30 June 2026) Bank Negara Malaysia (BNM) said headline inflation increased to 2.0% in May 2026 from 1.9% in April, while core inflation remained unchanged at 2.0%. The increase was mainly driven by higher prices for electricity, following the imposition of a surcharge due to increased generation costs, and vegetables. The increase was partly offset by lower inflation for domestic air travel and retail fuel, particularly RON97 and diesel. Credit to the private non-financial sector grew 6.4% in May from 5.8% in April, supported by stronger business financing, with outstanding corporate bonds rising 8.0% from 6.2% and outstanding business loans increasing 7.0% from 6.2%, primarily for working capital. Household loan growth remained steady at 5.5%. Manufacturing industrial production growth accelerated to 8.3% in April from 5.5% in March, with export-oriented industries expanding 8.5% due to higher production of electrical and electronics, refined petroleum and chemical products, while domestic-oriented industries grew 8.0%, supported by motor vehicles, food processing and construction-related materials. BNM said the ringgit appreciated 0.1% against the US dollar despite global uncertainties related to the West Asia conflict and US Federal Reserve policy expectations, outperforming regional currencies. The 10-year Malaysian Government Securities yield remained broadly stable, while the FTSE Bursa Malaysia KLCI declined 2.3% due to non-resident outflows.

THE PHILIPPINES
Rising global demand for Philippines’ ube outpaces domestic supply
(30 June 2026) Rising global demand for the Philippines’ ube is outpacing domestic supply, with the president of the Bohol Ube Growers Association stating that his group produces between five and eight tonnes every seven months but cannot meet requests for two tonnes per month, with ubi kinampay currently selling for PHP 90-100 per kilogram. Philippine ube exports exceeded USD 3 million in 2025, more than double the USD 1.4 million recorded in 2024, with key markets including Canada, the Middle East, Asia, the US, South Korea and Europe. The Department of Agriculture has announced plans to institutionalise the ube industry through standardisation and export-ready systems, allocating PHP 2.6 million to expand production, while the US Department of Agriculture has committed USD 34 million to strengthen the ube value chain, including processing. The Bohol Ube Growers Association said its association recently received a harvesting facility enabling production of ube powder, extending shelf life and increasing its value to PHP 1,800 pesos per kilogram. Bohol has applied for geographical indication (GI) registration for ubi kinampay to protect its origin, quality and market identity amid expanding production in Viet Nam and China. Researchers from the Philippine Root Crop Research and Training Centre said ube has become a high-value export crop with yields potentially exceeding 3 kg per plant and up to 20,000 plants per hectare under intensive cultivation, although seasonal production, disease susceptibility and the limited adaptability of the kinampay variety continue to constrain supply. Researchers are developing cultivation techniques and alternative varieties to support year-round production and improve competitiveness in the global ube market.

VIET NAM
Vietnam Airlines aims to remain profitable despite more challenging environment
(30 June 2026) Vietnam Airlines aims to remain profitable in 2026 despite higher jet fuel prices, exchange rate volatility and rising operating, maintenance, logistics and environmental compliance costs. The airline estimates average Jet A1 fuel prices of USD 128.54 per barrel in 2026, up nearly 48% from 2025, increasing fuel costs by an estimated VND 11.9 trillion, although prices have eased to USD 112-115 per barrel following the reopening of the Strait of Hormuz and a US-Iran ceasefire. Assuming fuel prices average USD 120 per barrel in the second half of 2026, Vietnam Airlines forecasts pre-tax profit of VND 101 billion for the parent company and VND 510 billion on a consolidated basis. The airline is implementing cost controls, optimizing its route network and improving fleet utilisation while expanding international services to Amsterdam, Phuket and Colombo and increasing frequencies to Singapore, Manila, Moscow, Kaohsiung, Melbourne and Sydney. It plans to invest in 50 new narrow-body aircraft for delivery between 2030 and 2032, lease 20 additional narrow-body aircraft for 2027-2028, introduce its first dedicated cargo aircraft in the third quarter of 2026 and expand infrastructure at key airports including Long Thanh International Airport. For 2026, Vietnam Airlines targets carrying 27.73 million passengers and 361,400 tonnes of cargo, up 8.1% and 6.2% year on year respectively, while consolidated revenue is projected to reach VND 138.9 trillion, an increase of more than 12%. The airline’s chairman said the airline will continue organisational restructuring and strengthening its workforce to support anticipated double-digit growth.

SINGAPORE
13.4% of resident households earn at least SGD 30,000 per month in 2025, up from 7.4% in 2020
(30 June 2026) Singapore’s 2025 General Household Survey showed continued growth in household incomes, with 13.4% of resident households earning at least SGD 30,000 per month, up from 7.4% in 2020. More than half of resident households (51.6%) earned at least SGD 12,000 monthly, compared with 38.2% five years earlier. Median monthly household market income reached a record SGD 12,446 in 2025, exceeding SGD 12,000 for the first time and increasing at an average annual real rate of 3.2% from SGD 9,099 in 2020. The survey attributed the shift towards higher income brackets to rising median earnings, with real annual income growth of 3.5% for Indian households, 3.1% for Chinese households and 2.3% for Malay households. Median monthly household market income in 2025 was SGD 13,382 for Indian households, SGD 12,969 for Chinese households and SGD 8,581 for Malay households. Employment accounted for almost 80% of total household market income. The survey also showed that dual-income households became more common, with 56.6% of married couples both employed in 2025, up from 52.5% in 2020, while households with only the husband employed declined from 24.9% to 21.0%, and households with only the wife employed remained broadly unchanged at 7.5%.


RCEP Monitor


AUSTRALIA
Headline inflation expected to peak at 4.25% in mid-2026, lower than 5% forecast in May federal budget
(28 June 2026) Australia’s Treasurer said headline inflation is now expected to peak at around 4.25% in mid-2026, lower than the 5% forecast in the May Federal Budget, supported by lower oil prices and progress in Middle East peace talks. He said inflationary pressures have eased more quickly than anticipated, although uncertainty surrounding the Middle East and the Strait of Hormuz continues to pose risks. The Treasurer also said underlying inflation is improving ahead of schedule, with updated Treasury forecasts to be released at the mid-year update, although he did not provide revised figures. Recent Australian Bureau of Statistics data showed annual headline inflation at 4.0%, below economists’ expectations of 4.3%, while trimmed mean underlying inflation was 3.6%, slightly above the 3.5% forecast. The May Federal Budget continues to project headline inflation declining to 2.5% by mid-2027. The Reserve Bank of Australia has raised the cash rate three times this year to 4.35% before pausing at its June meeting.

NEW ZEALAND
Improved business sentiments following early signs of US-Iran peace deal and lower fuel prices
(30 June 2026) ANZ Bank New Zealand’s business confidence index rose to 36.6 in June from 10.0 in May, the highest level since February, while the own-activity index increased to 36.9 from 25.6, reflecting improved sentiment following early signs of a US-Iran peace agreement and lower fuel prices. ANZ said firms appeared more willing to invest and hire despite continued uncertainty. The survey indicated easing inflationary pressures, with fewer firms expecting higher costs over the next three months, a net 50.7% planning to increase prices, and one-year inflation expectations declining to 3.36% from 3.63% in May. Profit expectations also improved, with a net 13% of firms expecting higher earnings over the next 12 months compared with 2% in May, while a net 9.4% expected to increase hiring, up from 3.4%. The results support expectations that New Zealand’s economy may perform better than previously anticipated following stronger-than-expected annual GDP growth through March, although economists continue to forecast a contraction in the second quarter before a recovery as fuel and other costs ease. Investors currently assign a 70% probability of a 25-basis-point Reserve Bank of New Zealand interest rate increase at the next policy meeting, although some economists expect any rate rise to be delayed until September or later.

SOUTH KOREA
South Korea tightens property market restrictions due to semiconductor boom spurring home prices
(30 June 2026) South Korea has expanded property market restrictions to Hwaseong’s Dongtan district, Yongin’s Giheung district and the city of Guri to curb speculative buying following sharp house price increases linked to semiconductor industry expansion and improved transport infrastructure. From 1 July, the three areas will be designated speculative zones subject to stricter lending restrictions, while land transaction permit requirements will take effect from 5 July. The land ministry said housing demand in Dongtan and Giheung has been driven by expectations of semiconductor industry growth and the GTX-A rail line, while Guri has benefited from its proximity to Seoul and redevelopment around rail stations. Gyeonggi Province said the measures are intended to prevent speculative demand from shifting into these areas due to their accessibility to Seoul and growth prospects. The government said it will strengthen housing market monitoring and accelerate housing supply plans to support market stability and protect end-users. Following the changes, 25 districts in Seoul and 15 in Gyeonggi Province will be subject to property market restrictions, as Seoul apartment prices have continued rising for a 73rd consecutive week despite earlier cooling measures.

15 participating countries

20 chapters

2.2 billion

US$26.2 trillion

28%

ASEAN member states, Australia, China, Japan, South Korea, New Zealand trade in goods and services, investment, intellectual property, e-commerce, competition, SMEs, economic and technical cooperation, and government procurement combined population, 30% world’s population combined GDP, 30% global GDP global trade (based on 2019 figures)